Category: Uncategorized

  • Dormant Bitcoin Wallet from 2011 Active, Moves 100 BTC Valued Over $8 Million

    Dormant Bitcoin Wallet from 2011 Active, Moves 100 BTC Valued Over $8 Million

    A Bitcoin wallet created in 2011 became active on Saturday, moving 100 BTC when the cryptocurrency’s price was nearing $82,000. The transaction, recorded at block height 967732, involved funds now valued at over $8 million.

    The wallet, initially established on November 2, 2011, had remained dormant for nearly 15 years. Its recent activity represents a notable on-chain event, drawing attention due to the age of the wallet and the quantity of Bitcoin moved.

    However, the implications of this movement remain uncertain. Holder intent cannot be determined from this data alone, and the transaction does not inherently signal a change in market direction or provide a definitive prediction of future price action. The implications are uncertain.

    On-chain analysts and cryptocurrency investors frequently monitor such events. While the activation of dormant wallets can sometimes indicate long-term holders liquidating or reallocating assets, attributing a specific motive or market impact without further information is speculative. This event underscores the dynamic nature of Bitcoin’s ledger, with older holdings potentially re-entering circulation.

    Why This Matters

    The materials describe a narrow update: A wallet created on November 2, 2011, moved 100 BTC when the price of Bitcoin was nearing $82,000. The wallet had been dormant for nearly 15 years.

    Broader Context

    Source materials place the factual news in this context: With bitcoin’s price almost hitting the $82,000 range on Saturday, at block height 967732, a wallet first created on Nov. 2, 2011, shifted 100 BTC worth more than $8 million using current bitcoin exchange rates.

  • Fed Rate Hike Boosts Bitcoin: The Significance Explained

    Fed Rate Hike Boosts Bitcoin: The Significance Explained

    Fed Rate Hike Fails to Dampen Bitcoin’s Spirits

    Following a significant setback for the CLARITY Act on September 15, financial markets turned their attention to the Federal Reserve the following day. The U.S. central bank implemented its first key interest rate increase in over three years, a move of 25 basis points.

    This development was widely anticipated to be bearish for risk-on assets such as Bitcoin (BTC). The decision, made with a unanimous 12-0 vote by policymakers, initially saw the cryptocurrency’s price dip. However, Bitcoin demonstrated remarkable resilience, swiftly recovering its losses and trading firmly in positive territory after the Fed’s announcement.

    Regulatory Setback Overshadows Rate Hike

    The U.S. Senate’s failure to pass the CLARITY Act had previously pushed Bitcoin to a multi-week low of $75,000. The market had braced for further declines, anticipating that a Fed rate hike on September 16 would exacerbate downward pressure. While a minor pullback did occur immediately after the Fed’s decision, Bitcoin quickly shrugged off these losses and began to climb as the week progressed.

    Nicolai Sondergaard, Senior Research Analyst at Nansen, noted that the regulatory setback had a more pronounced impact on Bitcoin’s volatility than the Federal Reserve’s action. He observed that Bitcoin performed better than higher-beta assets like Ethereum (ETH) and Solana (SOL) in the wake of these events.

    Iliya Kalchev, an analyst at Nexo Dispatch, commented on the unusual market reaction. “Bitcoin rose on the day the Federal Reserve delivered its first interest rate hike in three years,” he stated, acknowledging that such a move would typically be expected to negatively affect a non-yielding asset. However, Kalchev explained that markets had already priced in a greater than 90% probability of a 25-basis-point hike, leaving little room for surprise once the Fed confirmed the decision.

    ETF Outflows Highlight Regulatory Impact

    Kalchev further cited data from SoSoValue, indicating that spot Bitcoin ETFs experienced net outflows of approximately $450 million on September 15, followed by $296 million the next day. This trend, he argued, underscores that the CLARITY Act’s failure had a more significant impact on the market than the Federal Reserve’s rate decision.

    Treasury Yields Emerge as Key Indicator

    The current focus for the market is likely to be Treasury yields. The 10-year yield has recently surpassed 5%, making government debt a highly competitive investment against risk assets like Bitcoin. Kalchev suggested that Bitcoin’s increasing correlation with gold and its diminishing relationship with the Nasdaq could signal a shift in investor perception. He believes investors are increasingly viewing Bitcoin through a monetary and fiscal lens, rather than solely as a leveraged technology play.

    Looking ahead, Kalchev emphasized that inflation, employment figures, and Treasury yields will be more critical than the Fed’s meetings themselves. A cooling inflation rate and stabilizing yields would likely alleviate pressure on the largest cryptocurrency. Conversely, if these trends persist or worsen, Bitcoin’s resilience will face another significant test.

  • Clarity Act Stalls in Senate, Paving Way for Agency-Led Crypto Regulation

    Clarity Act Stalls in Senate, Paving Way for Agency-Led Crypto Regulation

    The US Senate’s failure to advance the Clarity Act, a landmark bill intended to structure the cryptocurrency market, has shifted the primary focus of regulatory efforts from Capitol Hill to federal agencies like the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC).

    The legislative path for comprehensive crypto market structure has been blocked, necessitating an immediate understanding of how agencies like the SEC and CFTC are now shaping the regulatory environment. This shift marks a pivotal moment, moving the primary locus of crypto regulation from Congress to federal agencies.

    The Clarity Act failed to garner the necessary 60 votes for advancement in a procedural vote on Tuesday, with the final tally at 49-50. The bill, which had been the subject of over a year of bipartisan negotiations, fell short due to partisan disagreements and political maneuvering. Senator Thom Tillis (R-NC) initially voted in favor but switched his vote to no, a procedural move that allows for the bill to be revisited.

    Following the legislative setback, regulatory bodies have stepped up their activities. On Thursday of the same week, the SEC released a new innovation exemption measure. This measure reportedly opens a pathway for tokenized U.S. stocks to trade on-chain, a development that has generated excitement within the industry. Concurrently, the CFTC issued a no-action position for passive software providers. The agency also submitted a broader crypto markets rulemaking proposal to the White House for review, though the specific details of this proposal are not yet public.

    The failure of the Clarity Act has coincided with finger-pointing between the parties. Republicans, including Senator Cynthia Lummis, a chief architect of the bill, accused Democrats of not being serious about passing the legislation. Conversely, some Democrats suggested that Republican leaders forced the vote prematurely. Despite the outcome, some senators involved in the negotiations, such as Senator Angela Alsobrooks, stated that the bill is not dead and that there remains a responsibility to regulate the industry, which involves over 70 million Americans.

    This legislative roadblock has contributed to fatigue within the industry, with many participants now looking to regulators for guidance rather than waiting for Congress to act. Kristin Smith, President of the Solana Policy Institute, noted that while Congress had opportunities, the political will was not present, making regulatory guidance the more viable path forward.

    The SEC’s new innovation exemption is seen by some as being explicitly tied to the Clarity Act’s failure to advance, indicating a proactive approach by the agency in response to Congressional inaction. The industry is now receiving clarity, albeit from regulators rather than lawmakers.

    However, uncertainties remain. The precise details of the CFTC’s broader crypto markets rulemaking proposal are not yet public, and the full implications of agency-led regulation are still unfolding. The immediate future of crypto regulation in the U.S. appears to be shaped by these agency actions, presenting both opportunities for innovation and potential for continued uncertainty.

    Why This Matters

    The materials describe a narrow update: The Senate failed to pass the Clarity Act, a crypto market structure bill, by a vote of 49-50, falling short of the 60 votes needed. The specific details of the CFTC’s broader crypto markets rulemaking proposal are not yet public.

    Broader Context

    Source materials place the factual news in this context: For anyone tracking the twists and turns of crypto policy in Washington, it was a long and bruising week.

  • Tether Mints $500 Million USDT on Solana in Under an Hour, Highlighting Network Demand

    Tether Mints $500 Million USDT on Solana in Under an Hour, Highlighting Network Demand

    Solana’s capacity for high-volume stablecoin operations is being tested, evidenced by Tether’s recent minting of $500 million USDT in under an hour. This rapid issuance increases Solana’s native USDT supply, which currently stands between $3.8 billion and $4 billion.

    Solana’s Growing Role in Stablecoin Operations
    Tether first deployed USDT on the Solana blockchain in September 2020, recognizing the network’s potential for high throughput and low transaction costs. For Solana’s ecosystem, stablecoin liquidity is foundational, supporting DeFi protocols for lending, borrowing, and liquidity provision, as well as facilitating settlement on trading platforms.

    Around the same period as Tether’s mint, Circle also minted $250 million USDC on Solana. The simultaneous expansion of supply by two major stablecoin issuers suggests that Solana is becoming a preferred venue for activities driving this demand.

    Market Demand Signals
    Market observers often interpret large stablecoin mints as leading indicators of demand rather than lagging ones, with new USDT signifying a need for liquidity from institutional trading desks, growing DeFi protocols, or exchanges replenishing reserves. However, the specific source of the demand for the newly minted USDT remains uncertain.

    Competitive Landscape
    While Tron remains the dominant network for global USDT circulation due to its established position in peer-to-peer transfers, Solana is carving out its niche by offering speed and cost advantages. Ethereum, meanwhile, continues to command the largest DeFi ecosystem.

    Tether also executed a $500 million USDT transfer to Binance via Solana during this period, further underscoring the network’s utility for high-volume operations. The competitive dynamic between Solana, Tron, and Ethereum for stablecoin market share is a significant factor in the ongoing development of crypto infrastructure.

    Conclusion
    The rapid minting of $500 million USDT by Tether on Solana, coupled with Circle’s concurrent USDC issuance, indicates Solana’s increasing significance in high-volume stablecoin transactions. While the precise reasons for this simultaneous expansion of supply by both issuers on Solana are not fully clear, the event underscores the network’s growing appeal for such operations.

    Broader Context

    Source materials place the factual news in this context: Tether first deployed USDT on Solana back in September 2020, betting early on the network’s high throughput and low transaction costs.

  • Trump Launches AI Task Force, Names AI Czar

    Trump Launches AI Task Force, Names AI Czar

    President Donald Trump has announced plans to establish an “AI Force” and appoint a dedicated “AI czar” to oversee the rapidly advancing artificial intelligence sector. This initiative signals the administration’s intention to consolidate AI policy under a single authority, a structure reminiscent of the “crypto czar” role previously created when venture capitalist David Sacks was tasked with a dual AI and cryptocurrency mandate in December 2024.

    Building on Existing Initiatives

    The new “AI Force” concept is an extension of the administration’s existing US Tech Force initiative, which was unveiled on December 15, 2025. That program aimed to recruit approximately 1,000 AI engineers and specialists, deploying them across various federal agencies, including the Department of Defense and the Treasury. The core objective is to integrate private-sector expertise into government operations, with companies such as AWS and Apple already participating in the initiative.

    The Sacks Precedent

    David Sacks, appointed as the White House AI and cryptocurrency czar on December 5, 2024, served as the model for this centralized oversight role. Sacks held the position until March 2026, during which time he advocated for a lenient regulatory approach to both AI and digital assets.

    Executive Order and Regulatory Landscape

    Executive Order 14179, signed on January 23, 2025, was specifically designed to remove obstacles hindering American leadership in AI. The order aimed to create a unified national policy framework, intended to override the fragmented landscape of state-level AI regulations that had begun to emerge across the country.

    Under Sacks’s influence, the administration took further steps. In May 2026, a proposed executive order that would have mandated extensive federal reviews of advanced AI models was withdrawn before implementation. The rationale was that prolonged review periods would impede development and grant an advantage to international competitors, particularly China.

    Stance on AI Safety

    President Trump has been unequivocal in his views on AI safety concerns. As of September 2026, he publicly dismissed the necessity of additional regulatory safeguards for AI technology, characterizing safety worries as exaggerated. His administration’s stance is that robust leadership, rather than new regulations, is the most effective means of mitigating potential AI risks.

    Synergies Between AI and Digital Assets

    David Sacks’s dual mandate underscored this philosophy. By combining oversight of both AI and digital assets under one individual, the White House signaled its view that these sectors are complementary rather than competing priorities.

    Opportunities for the Tech Sector

    The tech industry can anticipate an increase in federal contracts and collaborative opportunities. Companies already engaged with the Tech Force initiative are poised to strengthen their ties with government agencies. Cloud providers like AWS are expected to be significant beneficiaries, as the government seeks to rapidly modernize its AI capabilities without developing all necessary infrastructure internally.

    Reports from within the White House indicate internal discussions have highlighted a division between officials who advocate for oversight and those who perceive any regulation as a hindrance to competitiveness. This tension appears to have been largely resolved in favor of an innovation-first approach.

  • Grayscale’s Zcash ETF to Implement 3-for-1 Share Split Aiming for Broader Investor Accessibility

    Grayscale’s Zcash ETF to Implement 3-for-1 Share Split Aiming for Broader Investor Accessibility

    Grayscale has announced a 3-for-1 forward share split for its Zcash ETF (ZCSH), a strategic move designed to increase the accessibility of its shares for investors. This split will triple the number of outstanding shares and proportionally reduce the per-share price, with split-adjusted trading set to commence on September 30.

    The Zcash ETF, which began trading on August 25, 2026, has already garnered significant investor interest, attracting over $233 million in net inflows and accumulating approximately $890 million in net assets as of September 17. The fund has also demonstrated robust market activity, recording over $11 billion in cumulative trading volume since its late August launch.

    Shareholders of record on September 28 will receive two additional shares for every one currently held. The distribution of these new shares will occur after market close on September 29. Grayscale’s objective with this split is to make the ETF shares more accessible to a wider range of investors, potentially leading to a deeper order book and tighter bid-ask spreads, according to market analysis.

    Supporting this development, the underlying asset, ZEC, the native token of the Zcash protocol, has shown recent strength. ZEC traded between $1,478 and $1,521, reflecting an approximate 25% gain over the past week. This price momentum is occurring alongside strengthening network fundamentals, with Zcash’s hash rate climbing to nearly 32 GSol/s and its mining difficulty reaching approximately 291 million.

    The Grayscale Zcash ETF is notable as the first US-listed product offering exposure to ZEC within an ETF structure. The ETF leverages zero-knowledge proofs for shielded transactions, a key feature of the Zcash protocol.

    Looking ahead, the Zcash network is scheduled to undergo the NU7 network upgrade on November 5, 2026, an event intended to reduce block times on the network.

    It is important to note that while the share split aims to enhance accessibility, the total value of an investor’s holdings will remain unchanged by the transaction. The long-term impact on market liquidity and the ETF’s performance will likely be influenced by the continued strength of ZEC, broader market conditions, and the effects of the upcoming protocol upgrade.

    Why This Matters

    The materials describe a narrow update: Grayscale is implementing a 3-for-1 forward share split for its Zcash ETF (ZCSH) on the NYSE Arca. The exact impact of increased retail participation on bid-ask spreads and order book depth.

    Broader Context

    Source materials place the factual news in this context: Grayscale is splitting its Zcash ETF three ways, and no, nobody’s losing anything.

  • Bitcoin Rally Hits Major Hurdle

    Bitcoin Rally Hits Major Hurdle

    Bitcoin Recovers Sharply, Nearing Key Resistance Zone

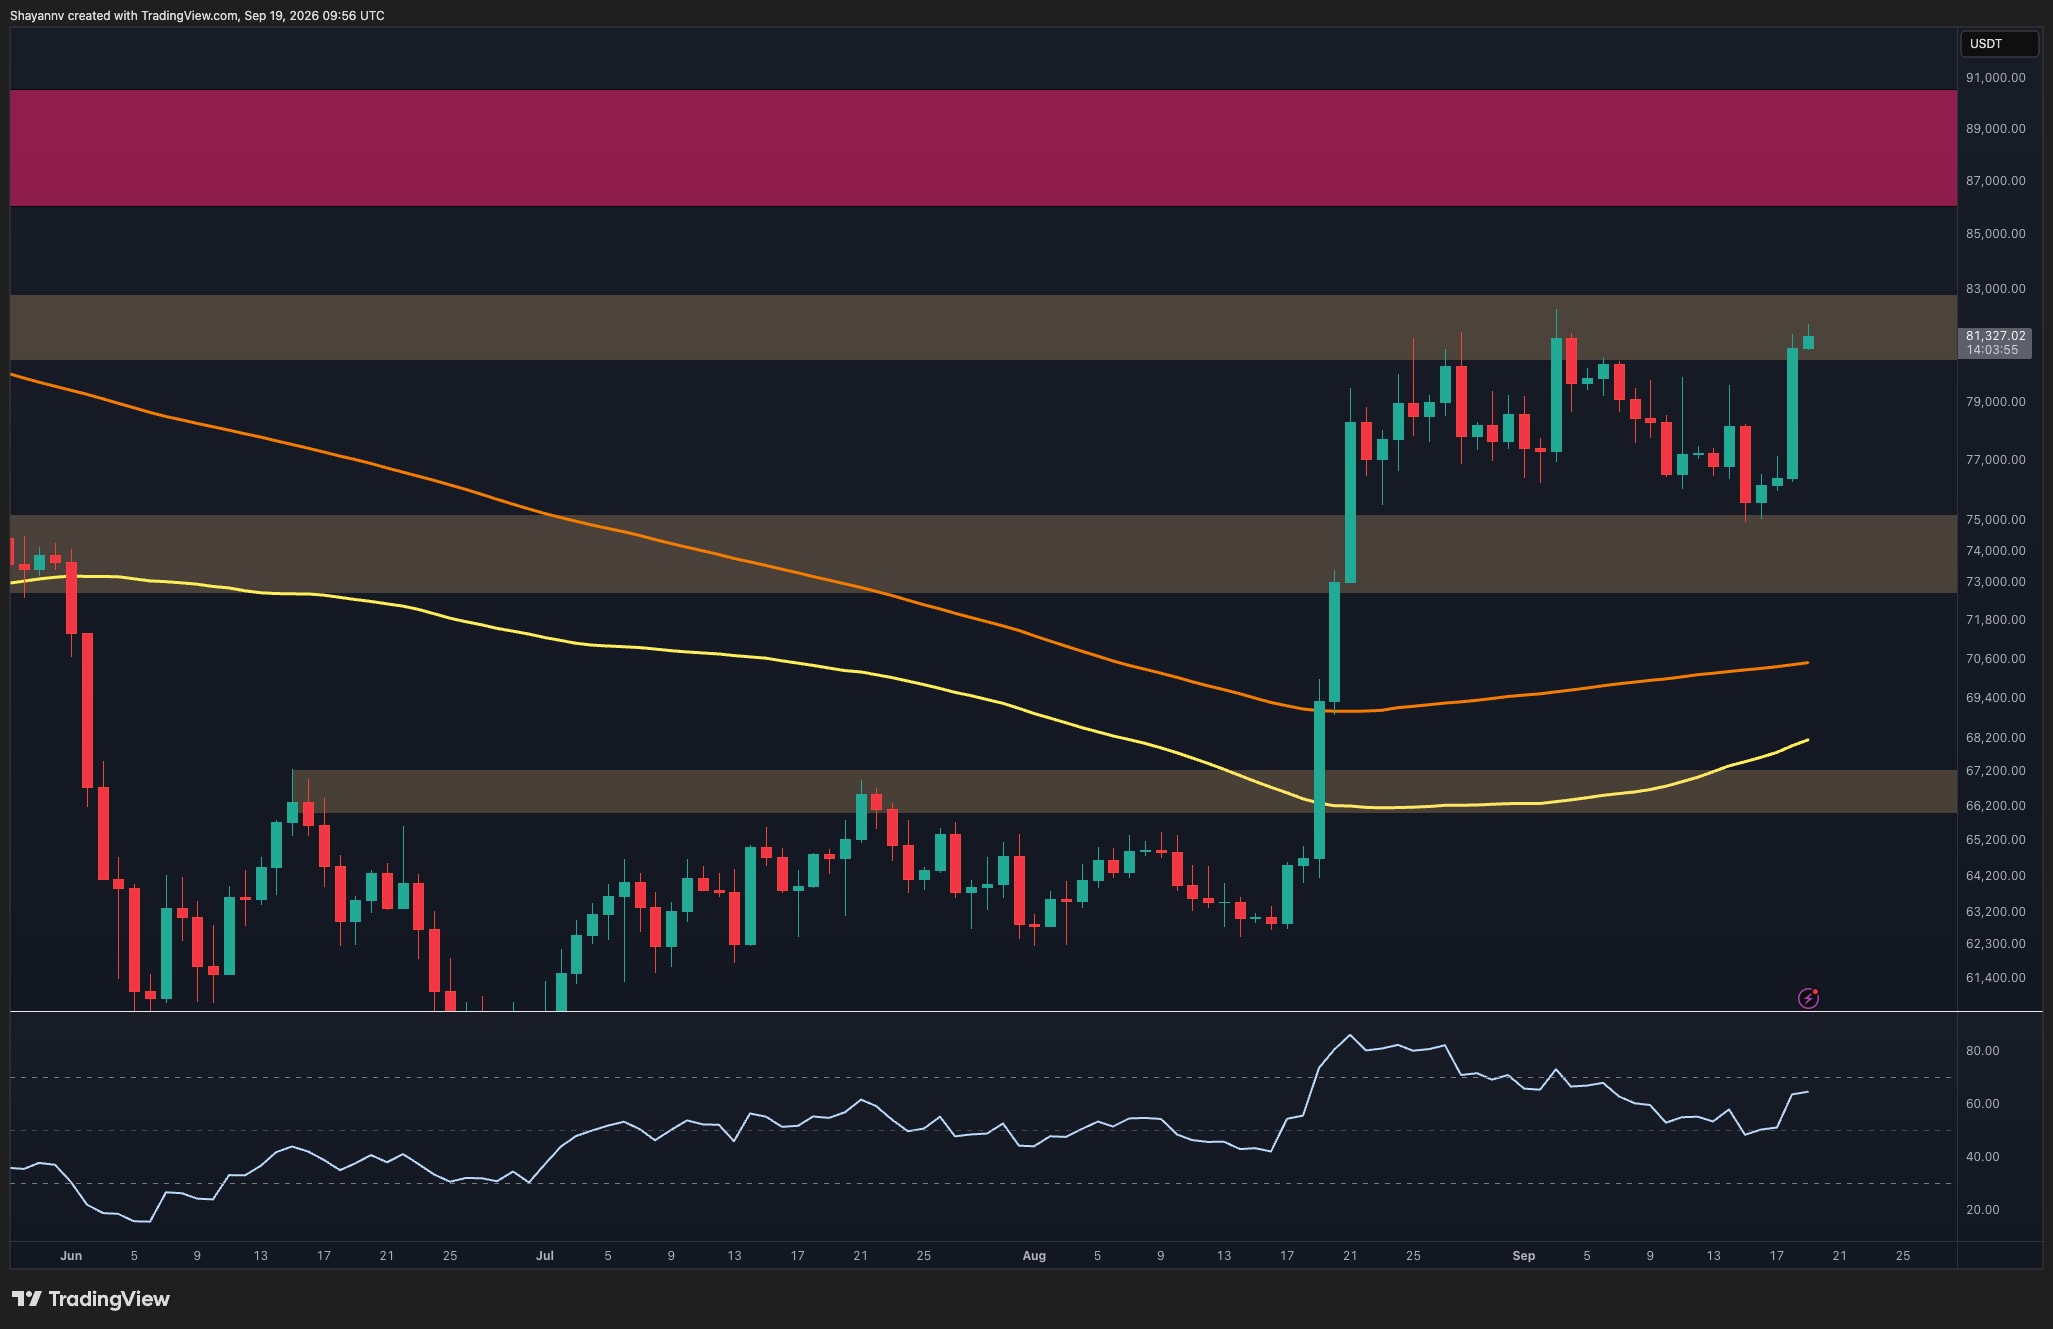
    Bitcoin has staged a strong recovery from its latest pullback, once again testing the upper boundary of its current consolidation range. With BTC trading around $81,500, the market is approaching a critical juncture where a confirmed bullish breakout could propel prices higher.

    Daily Chart Consolidation

    The daily chart indicates that Bitcoin has been consolidating following a significant breakout in August. The recent rebound from the $75,000 level has been particularly robust, with buyers swiftly pushing the price back towards the major resistance zone between $80,500 and $82,500.

    This area has consistently capped upward price movements and remains the primary hurdle for another bullish advance. Bitcoin is currently retesting this zone around $81,500, while the broader market structure remains constructive as long as the support area between $72,500 and $75,000 holds.

    Momentum indicators have also shown improvement. The daily Relative Strength Index (RSI) has moved back above the neutral 50 level and is approaching the mid-60s, signaling renewed buying interest without yet entering overbought territory.

    A sustained daily breakout above the $82,500 resistance level would represent a significant structural development and could open the path towards the next major supply zone, estimated between $86,000 and $90,000. Conversely, another rejection at this resistance could keep Bitcoin trading within its current range, with $75,000 and the broader $72,500-$75,000 region serving as the key support.

    Four-Hour Timeframe Insights

    The four-hour timeframe offers a clearer view of the range-bound structure. Bitcoin recently experienced an aggressive rebound from the lower boundary of its range, near $74,500-$75,000, and has now returned directly to the $81,000-$82,000 resistance region.

    This recovery has been impulsive, particularly the latest move from approximately $76,000 to $81,000. However, the price has yet to achieve a convincing breakout above the upper boundary. Consequently, the market remains within the broader range despite increasingly bullish short-term momentum.

    A clean break and sustained hold above the $81,000-$82,000 zone would likely shift the market structure decisively in favor of buyers. Such a move could trigger another price surge, initially targeting the rising upper trendline around $84,000-$85,000.

    Until this breakout occurs, rejection remains a plausible scenario. Failure to overcome the $82,000 level could send BTC back towards the middle of the range, with the $72,500-$75,000 zone continuing to act as critical support and the broader invalidation area for the current bullish setup.

    Liquidation Heatmap Analysis

    The two-week Binance BTC/USDT liquidation heatmap provides additional context for the recent rally. Liquidation heatmaps illustrate areas of concentrated leveraged positions, with brighter regions indicating larger potential liquidation clusters.

    Bitcoin’s surge above $80,000 has pushed the price into a significant concentration of liquidity within the $80,000-$82,000 region. This aligns closely with the technical resistance observed on price charts, making the current area particularly pivotal.

    Some liquidity remains immediately above the current market price, suggesting that a decisive breakout could trigger additional short liquidations and potentially accelerate the upward movement. This supports the possibility of another sharp spike if BTC successfully breaks through the $81,000-$82,000 resistance zone.

    Simultaneously, a liquidity concentration persists below the current price, around $74,000-$75,000. Therefore, as long as Bitcoin remains capped below resistance, volatility in either direction cannot be ruled out. For now, the combination of improving momentum and price pressing against the range high places the focus squarely on whether buyers can convert the current test into a confirmed breakout.

  • Hyperliquid Posts $3M Daily Revenue Amidst Onchain Protocol Surges

    Hyperliquid Posts $3M Daily Revenue Amidst Onchain Protocol Surges

    Onchain Platforms See Surge in Protocol Revenue, Hyperliquid Leads Pack

    A wave of robust performance has swept across decentralized finance, with four major onchain platforms simultaneously reporting their strongest weekly revenue figures. Hyperliquid, a decentralized derivatives exchange, spearheaded this surge, raking in $3.07 million in protocol revenue within a single 24-hour period.

    Data compiled by DefiLlama reveals that Hyperliquid’s seven-day revenue total reached approximately $13.47 million. This achievement solidifies its standing as one of the most profitable protocols in decentralized finance, excluding stablecoin issuers.

    Joining Hyperliquid in this notable performance were three other platforms: Pump (pump.fun), StonkFun (Stonk), and Pons. Each of these protocols also set new personal weekly revenue records.

    Hyperliquid’s revenue generation is primarily driven by perpetual futures trading. The protocol directs nearly 99% of eligible perpetual futures fees into its Assistance Fund, which is then used for HYPE token buybacks and burns.

    StonkFun, which operates within the token launchpad sector, recorded a peak single-day revenue of $1.84 million during the same period. Pons demonstrated remarkable consistency, generating around $17.8 million in revenue over its trailing 30-day window.

    Pump, a memecoin launchpad built on the Solana blockchain, completed the quartet. Its strong performance is attributed to the sustained activity within the Solana ecosystem.

    When stablecoin issuers like Tether and Circle are excluded, DefiLlama’s rankings now position these protocols among the leading onchain revenue generators. This distinction is significant, as stablecoin revenue models are fundamentally based on interest income from reserves, differing from the user-generated protocol fees that drive the other platforms.

    Activity levels saw a notable increase around mid-September, leading to frequent shifts in revenue leadership among these platforms.

    Hyperliquid employs a particularly aggressive strategy, channeling almost all eligible fees into its Assistance Fund for HYPE token buybacks and burns. In contrast, the launchpad protocols typically allocate their earnings between treasury accumulation and token buyback initiatives.

    For Hyperliquid, the $13.47 million in weekly revenue translates to an annualized run rate exceeding $700 million.

  • Ethereum Surges as Whales Accumulate, Wallet Count Peaks

    Ethereum Surges as Whales Accumulate, Wallet Count Peaks

    Ethereum Surges Past $2,600 Amidst Whale Activity and Staking Growth

    Ethereum’s recent ascent beyond the $2,600 mark has been propelled by a confluence of factors, including a resurgence in whale transactions, a record number of non-empty wallets, and significant developments in the realm of staking, according to data from Santiment Intelligence.

    While an increase in whale transactions doesn’t definitively signal accumulation, as large transfers can represent both buying and selling, the price action of Ether (ETH) has shown a clear inclination towards purchases.

    Santiment’s analysis reveals that the number of non-empty Ethereum wallets has reached an all-time high, exceeding 207 million. This growth indicates a continued broadening of ETH ownership, even after periods of subdued price performance. Concurrently, a substantial portion of Ethereum’s circulating supply remains committed to staking, rather than being held idly.

    With entities like Bitmine actively staking significant token holdings, the total amount of ETH currently staked has surpassed 40 million. Furthermore, Ethereum continues to dominate the decentralized finance (DeFi) landscape, boasting a total value locked (TVL) of approximately $50 billion.

    This combination of on-chain metrics underscores the underlying strength behind Ethereum’s latest recovery, which saw the leading altcoin rebound from below $2,400 to its current position above $2,600. Ethereum’s investment appeal appears to extend beyond short-term price speculation, with the asset deeply integrated into staking, stablecoins, lending, decentralized exchanges (DEXes), and other DeFi applications.

    Adding to the positive momentum, the cost of transacting on the Ethereum network has become significantly more affordable. The average transaction fee has fallen to below $0.10, representing a decrease of over 85% from its peak of $0.72 in April.

    This improving on-chain environment coincides with Ethereum approaching a critical technical resistance level. Popular analyst Ted Pillows has identified the current resistance zone as a significant hurdle for ETH’s recovery, suggesting that a sustained breakout could pave the way for new local highs.

    On a shorter timeframe, Pillows indicated that a weekly close above $2,550 would strengthen ETH’s potential to reach the $2,900-$3,000 range, a projection echoed by recent analysis from Ali Martinez. Looking further ahead, the long-term outlook for Ethereum appears even more optimistic. Pillows has set an ambitious target of $10,000 for the asset, citing its need to “catch up with global M2 supply.”

    [Image: A tweet from Ted Pillows stating “Ethereum has a lot of catching up to do with global M2 supply. $10,000 ETH remains the target by 2029.”]

  • CLARITY Act Uncertainty Fuels Wall Street Blockchain Adoption

    CLARITY Act Uncertainty Fuels Wall Street Blockchain Adoption

    Senate’s CLARITY Act Fails Procedural Vote, SEC Unveils “Innovation Exemption” for Tokenized Stocks

    Washington D.C. – The U.S. Senate’s CLARITY Act, a landmark piece of legislation aimed at structuring the digital asset market, failed a procedural vote by a narrow margin of 49 to 50. Just two days later, the Securities and Exchange Commission (SEC) issued an “Innovation Exemption,” effectively greenlighting the on-chain trading of tokenized U.S. stocks.

    Financial commentator Wen Hongjun believes this outcome, while seemingly a setback for legislative certainty, may actually accelerate Wall Street’s migration to the blockchain. The exemption, he argues, truly elevates the importance of trading pair rules, with compliant payment stablecoins now directly integrated into the settlement leg of the U.S. stock market on-chain.

    Who Will Be the Market Maker, Which Chain Will Be Used, Whose Pool Will Be Tapped, and Whose Currency Will Set the Price?

    On September 15th, the U.S. Senate’s procedural vote on the CLARITY Act (Digital Asset Market Structure Act) fell short of the 60-vote threshold, failing 49 to 50. This significant deficit, a full 11 votes shy of the supermajority, has drastically reduced market predictions for its legislative success this year from over 80% in February to single digits.

    On September 17th, the SEC unveiled its “Innovation Exemption,” permitting qualified “Tokenized Securities Trading Venues” (TSVs) to utilize licensed Automated Market Maker (AMM) liquidity pools for the on-chain trading of tokenized U.S. equities.

    This timing is not coincidental but rather a strategic division of labor. As Paul Atkins stated in his announcement, “With Congress unable to advance the CLARITY Act this week, the SEC is taking a step forward today within its statutory authority.” In simpler terms, when Congress cannot provide certainty, the executive branch takes action.

    Legislation aims to provide “legal certainty” to industries, but Wall Street has never waited for approval to innovate. What it requires is a pathway that ensures “doing so won’t lead to prosecution.” The failure of the CLARITY Act has seen the SEC’s Section 36(a) exemptive authority fill the void. While the path may differ, the direction remains unchanged.

    Administrative exemptions are faster than legislation but are considerably more fragile, with a five-year sunset clause, temporary status, and conditional terms. The next administration could revoke it, courts could challenge it, and a change in SEC leadership could rewrite it. The industry is well aware that if Congress cannot deliver, the focus shifts back to how much space the SEC and CFTC can unlock under existing laws.

    In essence, the industry has traded “legislative permanence” for “administrative speed.” This is a time-bound transaction.

    The roadblock this time was not technical provisions but ethical clauses. Democrats demanded enforceable bans on profits from cryptocurrency for presidents and high-ranking officials during rule-making periods. Republicans, on September 14th, presented a 630-page version incorporating 126 amendments requested by Democrats, yet still failed to secure votes. Furthermore, if the Senate shifts hands after the midterm elections, the Banking Committee could be led by Elizabeth Warren.

    My conclusion is that the failure of the bill does not mean the migration to the blockchain will stop. I have repeatedly emphasized that Trump will not disappoint, and the bill’s failure will actually accelerate the migration. Because the window is only five years, and it’s first-come, first-served, the migration of talent, capital, and industry officially begins this week. Once the industry has migrated to the blockchain, and the interests of Wall Street financiers behind the Democratic Party are secured, the deed will be done. Will subsequent legislation fail? Or will it pass under a different name, with the benefits merely redistributed to their own financiers?

    Technical Breakdown: Four Key Points

    • Dual Exemption: TSVs are exempted from the definition of “exchange,” and market makers providing liquidity in their own capital within the pool are exempted from the definition of “dealer.”
    • Must Be True Equity: Tokens must retain corresponding dividend and voting rights; synthetic versions are explicitly prohibited. Robinhood’s Stock Tokens, Kraken’s xStocks, and Ondo’s offshore products only offer price exposure without shareholder rights. Their current forms cannot enter this arena and must restructure their products to do so.
    • Permissionless Chain + Permitted Participants: Smart contracts must be auditable, public, and deployed on a “public, permissionless” distributed ledger. However, participants are permitted, limited to U.S. persons, and must comply with sanctions regulations. This provision effectively blocks two types of entities: traditional institutions seeking to launch private consortium chains and DeFi purists aiming for fully open, KYC-free pools.
    • Strict Controls: There are caps on the number of listed tickers and trading volumes. Trading must halt in sync with primary listing exchanges. Issuers must be notified in writing before third-party tokenization, with the right to object.

    Most media outlets have covered the above points. What truly warrants amplification are the trading pair rules.

    Under the exemption, tokenized U.S. stocks can only be traded against three types of assets: another tokenized NMS stock, non-security crypto assets (such as stablecoins issued by compliant payment stablecoin issuers), or tokenized money market funds. Each pair constitutes an independent pool, with its own reserves and pricing.

    The SEC has directly incorporated “compliant payment stablecoins” into the settlement leg of the on-chain U.S. stock market.

    This represents a leap in the positioning of stablecoins, elevating them from “transaction mediums within the crypto sphere” and “cross-border payment tools” to units of account and settlement assets in the U.S. capital markets. The GENIUS Act provided them with legal status, and the Innovation Exemption has provided them with use cases.

    Even more intriguing is the third option: tokenized money market funds. The GENIUS Act prohibits interest payments on payment stablecoins, forcing the on-chain “cash leg” to bifurcate into two forms:

    • Non-interest-bearing payment stablecoins: Pure settlement, high liquidity, and pricing benchmarks.
    • Interest-bearing tokenized MMFs: Capital parking and yield accrual (e.g., BUIDL, BENJI, USTB).

    Wall Street’s familiar tiered cash management system is being meticulously rebuilt on-chain. Whoever’s cash leg is chosen as the primary trading pair will simultaneously gain three advantages: float, order flow, and pricing benchmarks.

    This is where market making truly lies. It’s not about who lists the most stocks, but about whose cash leg becomes the market’s unit of account.

    • Issuer Layer: Circle/USDC, banks and payment consortia like the OUSD camp, and brokerage firms’ own stablecoins – who will become the default pricing currency for tokenized U.S. stock pools?
    • Public Chain Layer: Ethereum, Solana, and BNB Chain, by meeting the criteria of “public and permissionless,” can directly serve as settlement networks for TSVs, indirectly benefiting from the spillover of compliant trading volume. The phrase “public and permissionless” is the biggest hurdle for traditional institutions building their own closed chains.
    • Platform Layer: DeFi mainstays like Uniswap, Hyperliquid, and Aave are essentially gaining a compliant lane, but KYC gates and other guardrails will limit their speed. Their positions differ: Uniswap is an AMM model directly written into the exemption; Hyperliquid, with its on-chain order book architecture, is already in discussions with regulators for implementation pathways but hasn’t secured a position in this round; Aave represents the next step, where tokenized U.S. stocks, once eligible as collateral, will open the door to leverage and re-collateralization for lending protocols.

    DeFi will henceforth be formally bifurcated into two worlds: “permissioned pools” and “permissionless pools.” The divergence point is not technology but the willingness to implement KYC.

    • Asset Side: Names like Securitize, Superstate, Ondo Finance, and Dinari, already involved in tokenization, are the most obvious early applicants. Ondo is particularly noteworthy, appearing on two lists: its existing offshore Global Markets product is ineligible due to offering only price exposure, but it acquired Oasis Pro in 2025, securing SEC-registered broker-dealer, ATS, and transfer agent licenses. Oasis Pro was one of the earliest institutions in the U.S. approved to settle digital securities with fiat currency or stablecoins like USDC and DAI. While its offshore products need modification, its onshore licenses are ready, representing a strategic approach for the five-year window.

    Licenses, cash legs, and chains are all indispensable. Those possessing only one are merely supporting the U.S. (dollar and Treasury bonds).

    The market’s reaction over the past two days has been telling: Securitize up nearly +15% in a single day, UNI up nearly +18% in 24 hours, Bullish up +6%, with Coinbase and Robinhood rising in tandem.

    It’s also important to remember a parallel second path: In March of this year, the SEC approved Nasdaq’s proposal for tokenized trading of Russell 1000 constituents and index ETFs, with full launch planned for October, utilizing the existing NSCC/DTCC clearing pipeline. The same company will soon have two stock markets: one operating through Wall Street’s old pipes, and another through public chains and AMMs. They will compete directly for the same underlying assets.

    The market’s appetite is already evident: Token Terminal data shows the scale of tokenized stocks approaching $3.2 billion, with year-over-year growth exceeding 1200%. Over the past 30 days, DEX trading volume reached approximately $15.75 billion, with nearly $3 billion occurring over weekends when NYSE and Nasdaq are closed. That $3 billion over the weekend represents demand that the old system cannot accommodate.

    Stablecoins have been upgraded from “payment/remittance tools” to “units of account and settlement in capital markets.” Their demand now extends beyond crypto trading to 24/7 U.S. stock trading, including weekends. This is a pool of entirely different magnitude.

    While the GENIUS Act’s prohibition of interest on stablecoins might seem to weaken them, the exemption’s inclusion of tokenized MMFs in trading pairs effectively permits the coexistence of a “non-interest-bearing settlement layer” and an “interest-bearing parking layer” on-chain. The tiered cash management system on-chain has truly taken shape at this moment.

    This is what Wall Street is truly vying for. Whichever “currency” (in reality, all are dollars) becomes the primary trading pair determines the price benchmark, liquidity depth, and settlement rhythm. Today, the door to trading has opened; tomorrow, the door to collateral will open. The key to both doors is “stablecoins,” a.k.a. Hayek’s “on-chain dollars” born from free competition in currency.

    The U.S. has integrated stablecoins into the infrastructure of its capital markets. Taiwan’s VASP special law and central bank are still discussing them within the framework of “payment tools.” This gap in positioning is more dangerous than any technological disparity.

    My view from Series-8 remains unchanged: general-purpose retail TWD stablecoins will struggle to find clear use cases in the short term. However, this exemption serves as a reminder: the real battlefield is not retail payments but the settlement leg of capital markets.

    Taiwanese brokerages and financial holding companies should not be asking “whether to issue stablecoins,” but rather: “Within this five-year window, do we have the capability to connect to the cash leg, custody leg, and settlement leg of on-chain U.S. stocks?”

    Taiwan holds a critical position in the global AI computing power supply chain. It should leverage this physical advantage to gain a voice in on-chain U.S. dollar settlement.

    The failure of the CLARITY Act proves only one thing: rules may lack clarity, but the migration of technology and innovation will not wait for you.

    Stablecoins are not just settlement networks for new ledgers; they are becoming Wall Street’s new battleground. And the true game of the “Innovation Exemption” has never been about “whether stocks can go on-chain.” It’s about who will be the market maker, which chain will be used, whose pool will be tapped, and whose currency (the dollar) will set the price.

    CLARITY is not dead! Senator Tillis calls for a re-vote, industry shifts focus to SEC/CFTC rulemaking.
    After CLARITY Act’s failed bid, a move is made: U.S. CFTC submits crypto regulation draft to the White House, proposing a dedicated compliant market.
    “Wen Hongjun’s Stablecoin New Finance 20”: One year of America’s genius bill! Crypto narrative fully taken over by traditional finance, where is Taiwan’s strategy?