Tag: Neutral

  • Market Skepticism Shadows US-Iran Ceasefire Outlook

    Market Skepticism Shadows US-Iran Ceasefire Outlook

    Prediction markets are signaling skepticism about the longevity of the current 14-day ceasefire between the United States and Iran. A key Polymarket contract, designed to track a continuous 14-day period without a US airstrike or surface-to-surface missile strike directly hitting Iranian territory, saw its value drop from over 60% to approximately 53% today.

    Traders are currently pricing in roughly 50-50 odds regarding the US’s ability to sustain a hold on military action for two full weeks. This cautious outlook is informed by recent events: the US and Iran had observed a third consecutive day of holding fire by Monday, following 13 consecutive nights of US strikes. However, President Donald Trump indicated to Axios that “very strong military action” remained an option if talks falter.

    Adding to the uncertainty, Iran has denied that direct negotiations are underway, stating that mediators are conveying messages. This lack of direct communication contributes to the prevailing ambiguity surrounding the situation.

    Historical Context and Market Reactions

    Past ceasefires have shown a correlation with market movements. A ceasefire in April, for instance, coincided with a sharp rise in Bitcoin and oil markets. However, analysts at the time characterized that period as “fragile breathing room.” In the days following that April ceasefire, prediction markets still reflected doubts about the normalization of shipping in the Strait of Hormuz, as some ships were reportedly rerouting.

    Future Talks and Market Outlook

    A separate prediction market, Myriad, tracks whether formal senior-level US-Iran peace talks commence by July 31. Its rules exclude preliminary discussions, meaning most funds in this market are allocated to the possibility of conversations being delayed until August. The July 31 Polymarket contract allows for this extension, as the required 14-day no-strike period only needs to begin by the July 31 deadline.

    The uncertainties surrounding the duration of the current ceasefire, the potential for renewed military action, and the nature of future diplomatic engagements contribute to a cautious outlook. While a period of reduced hostilities has been observed, market indicators suggest a significant degree of doubt about its sustained continuation.

    Why This Matters

    The materials describe a narrow update: Prediction markets have lowered their assessment of the likelihood of a sustained 14-day ceasefire between the US and Iran, indicating skepticism about its duration. The duration of the current US ceasefire with Iran.

    Broader Context

    Source materials place the market analysis in this context: The United States seems to have announced a ceasefire yesterday on its offensive actions against Iran.

  • Crypto Figures Voice Concerns Over Government AI Knowledge Control

    Crypto Figures Voice Concerns Over Government AI Knowledge Control

    Concerns are mounting within the cryptocurrency community regarding the potential for governments to dictate the knowledge and capabilities of artificial intelligence systems. Figures like Erik Voorhees have voiced alarms that such control could set a dangerous precedent for defining ‘safe’ intelligence, sparking a broader debate on AI oversight and regulation.

    On July 28, Erik Voorhees argued on X (formerly Twitter) that states should not be the arbiters of what forms of intelligence are deemed ‘safe.’ He warned that allowing governments to define acceptable AI knowledge could expand beyond its original purpose, potentially leading to restrictions on encryption or the obstruction of government orders. Voorhees hypothesized a progression where rules against discussing bioweapons could evolve into broader censorship, stating, “Civilization must not permit the state to determine what manner of intelligence is ‘safe.’” He suggested that only the United States possesses the cultural character to resist such an outcome, and if it fails, “nowhere will it be preserved.”

    David Schwartz, replying to Voorhees’ post, echoed the sentiment with “Yes, this. Exactly this.” Bird also responded, questioning, “The moment someone gets to decide what knowledge is ‘safe,’ where does it stop?”

    This discussion emerged amidst a fresh debate over AI oversight. The conversation gained traction after Anthropic, an AI safety research company, published a statement from CEO Dario Amodei pushing back on claims that the company advocated for banning open-weight models. Amodei insisted that Anthropic has never advocated for such a ban and argued that open-weight systems can provide value when they do not possess dangerous capabilities. Anthropic’s concerns, however, focus on authoritarian governments developing AI for military or surveillance uses, and the potential for misuse in cyberattacks or biological threats. The company supports restrictions on access to advanced chips, action against industrial-scale data distillation, and safety testing for highly capable AI systems.

    The tension over who should police AI also surfaced earlier in July when Demis Hassabis, CEO of Google DeepMind, proposed a federally backed body to test and certify frontier AI models before their release. Sam Altman, CEO of OpenAI, called Hassabis’ idea “thoughtful,” and Satya Nadella, CEO of Microsoft, welcomed it as a way to prevent models from causing serious harm. However, Brian Armstrong, CEO of Coinbase, rejected the proposal, arguing it would add another layer of approval processes. Armstrong suggested that existing fraud, tort, and consumer protection laws are sufficient to address potential AI harms.

    The Information recently reported that the Trump administration was finalizing a framework for AI companies to voluntarily submit advanced models for government testing. This reported initiative adds another layer to the ongoing discussions about AI regulation and oversight.

    These differing viewpoints highlight a division within the tech industry regarding the necessity and structure of AI regulation. While some leaders advocate for robust testing and certification, others believe existing legal frameworks are adequate and new regulatory bodies could stifle innovation. The core uncertainty remains about the extent to which governments should control AI knowledge and capabilities, and what the long-term implications will be for technological development and societal safety. The debate is ongoing, with significant questions about the future of AI oversight yet to be resolved.

    Why This Matters

    The materials describe a narrow update: Crypto figures, including Erik Voorhees, are raising alarms about governments potentially dictating what AI systems can know or discuss, citing concerns that this could set a dangerous precedent for defining ‘safe’ intelligence. The exact scope and nature of the Trump administration’s proposed AI testing framework.

    Broader Context

    Source materials place the factual news in this context: The post landed in the middle of a fresh debate over how much oversight AI companies should accept.

  • XRP Price Hinges on Fed Rates, Ripple ETF Flows

    XRP Price Hinges on Fed Rates, Ripple ETF Flows

    XRP Price Prediction Mixed Amid Fed Uncertainty and ETF Flows

    XRP’s price is hovering near $1.50, reflecting a roughly 5% decline over the past 24 hours, as traders brace for the Federal Reserve’s policy meeting scheduled for July 28-29. The broader economic outlook remains cautious, though data on exchange-traded fund (ETF) flows may indicate underlying resilience. Bitcoin also experienced a dip, trading around $63,450 after a brief ascent above $64,900, underscoring a defensive sentiment across major cryptocurrencies.

    Seven US spot XRP ETFs have been active since late 2025. While inflows have moderated from earlier in the year, they have not translated into sustained outflows. This discrepancy between consistent ETF demand and subdued price action is a scenario that analysts closely monitor, suggesting that institutional interest may persist despite short-term selling pressure.

    However, market expectations regarding the Federal Reserve have evolved. The consensus now largely anticipates interest rates remaining unchanged, with a surprise 25-basis-point hike considered a less probable outcome. This shift renders forecasts based on an immediate 25- or 50-basis-point rate cut obsolete. Nevertheless, some analysts maintain that a loosening of monetary policy later this year could bolster XRP’s recovery, particularly in conjunction with ongoing ETF demand.

    Meanwhile, Bitcoin’s persistent negative Coinbase premium signals muted institutional spot buying. This is a relevant factor, as XRP has historically underperformed during periods of risk aversion before experiencing rapid recoveries when market sentiment improves. Currently, traders appear to be focusing on the Fed’s decision as the next significant catalyst for both Bitcoin and XRP.

    Technical Outlook and Potential Scenarios

    At $1.05, XRP is trading at the lower end of its recent intraday prediction range, which spans from $1.05 to $1.09. The price compression observed in recent weeks is poised for a key catalyst, with the Fed’s July 29 policy statement potentially triggering a sharp directional move.

    Immediate resistance is identified around the $1.18 to $1.20 mark, representing the first significant technical barrier. A breach above this level, supported by renewed buying pressure, could pave the way towards $1.22 to $1.32. Conversely, immediate support lies at $1.05. A decisive break below this level could expose the $0.95 to $1.00 zone, where longer-term buyers might emerge.

    A bullish scenario hinges on a dovish Federal Reserve stance and increased institutional demand. Should these conditions materialize, XRP could retest the $1.20 level and aim for a move towards $1.35. A sustained rally would also bring longer-term targets, such as Standard Chartered’s year-end forecast of $2.80, back into consideration.

    The base case scenario anticipates a Fed pause accompanied by dovish commentary. This could propel XRP towards the $1.15 to $1.20 range before momentum wanes and consolidation sets in. Conversely, a hawkish surprise from the Fed could push XRP back towards $1.00 or even $0.95. A daily close below $1.00 would undermine the current bullish outlook.

    One encouraging indicator remains institutional demand, with ETF-related products continuing to attract capital even as XRP trades near recent lows. This divergence suggests that selling pressure is being absorbed, although the price needs to reclaim resistance levels to confirm a stronger upward trend.

    Broader Market Considerations and Emerging Opportunities

    XRP’s current price point of $1.05 presents a clear macro trading opportunity, though its upside is constrained by a market capitalization already exceeding $60 billion. The Fed’s decision is a significant catalyst, with a potential 10-20% price movement achievable.

    For traders seeking exposure to Bitcoin-ecosystem catalysts with early-stage pricing advantages, established large-cap cryptocurrencies may appear less compelling.

    Bitcoin Hyper, currently in its presale phase at $0.0136838 and having raised nearly $33 million, positions itself as the first Bitcoin Layer 2 solution integrating the Solana Virtual Machine (SVM). This combination aims to leverage Bitcoin’s security and trust layer with sub-Solana execution speeds and programmable smart contracts.

    The project’s Decentralized Canonical Bridge facilitates native BTC transfers, aiming to eliminate custodial complexities that have historically deterred institutional capital from Bitcoin DeFi. Staking is currently live, offering high APY for presale participants.

    For active traders observing XRP’s range-bound movement ahead of a macro binary event, researching Bitcoin Hyper before the presale concludes offers a straightforward risk-sizing exercise. It is also prudent to monitor how the Fed’s decision influences positioning across the broader cryptocurrency market. The outcome of the rate decision will reset the risk appetite framework for all digital assets, from large-cap to early-stage projects.

  • Bybit to Support Stacks v4.0.1 Upgrade

    Bybit to Support Stacks v4.0.1 Upgrade

    Bybit to Support Stacks Network Upgrade

    Cryptocurrency exchange Bybit has announced its support for the upcoming Stacks (STX) v4.0.1 network upgrade. The upgrade is scheduled to occur on July 29, 2026, at approximately 03:00 AM UTC, coinciding with Bitcoin block height 960,230.

    To facilitate a seamless transition, Bybit will temporarily suspend Stacks (STX) deposits and withdrawals starting at 02:30 AM UTC on July 29, 2026. Trading activities on the platform will remain unaffected during this period.

    Bybit has stated that there will be no further announcements regarding the resumption of deposit and withdrawal services. Users seeking to be notified when these services are back online are advised to visit the Deposit or Withdrawal page and activate the “Set Alert” function.

    Further details about the Stacks network upgrade can be found in the official release notes.

  • Crypto Industry Boosts Political Spending Amid Push for CLARITY Act Before Senate Recess

    Crypto Industry Boosts Political Spending Amid Push for CLARITY Act Before Senate Recess

    The U.S. cryptocurrency industry, with Ripple at the forefront, is significantly intensifying its political donations and lobbying efforts, aiming to influence the passage of the CLARITY Act before the Senate’s August recess. This heightened activity places the sector among the largest corporate political spenders this election cycle.

    According to Public Citizen, crypto companies have collectively spent approximately $189 million, representing about 37% of all corporate election spending. This figure substantially exceeds the contributions from sectors like artificial intelligence and Big Tech ($60 million) and online gambling ($45.6 million), positioning the crypto industry as the leading corporate political spender.

    Ripple is identified as a major contributor, with Public Citizen estimating its donations at around $48 million for the 2026 election cycle. A significant portion of this funding is channeled through Fairshake, the industry’s primary super PAC network. Fairshake and its affiliated committees reported holding approximately $193 million in cash prior to the 2026 midterms. During the latter half of 2025, major players including Coinbase, Ripple, and Andreessen Horowitz committed about $74 million. Ripple’s largest disclosed contribution to Fairshake was a $25 million commitment made in late 2025.

    Fairshake operates through three entities: a main super PAC, Protect Progress (supporting Democrats), and Defend American Jobs (supporting Republicans). This multi-pronged approach allows donors to support candidates across the political spectrum, often targeting low-turnout primaries where modest advertising budgets can sway competitive races.

    During the 2023-2024 election cycle, Fairshake and its affiliates raised about $93 million and spent over $130 million to support favored candidates. While campaign spending is not the sole determinant of electoral success, the industry’s increased political engagement has coincided with growing congressional support for crypto legislation.

    The CLARITY Act, a pivotal piece of legislation for the industry, has already passed the House and is now before the U.S. Senate. With the Senate recess scheduled to begin on August 7, 2026, lawmakers have approximately 10 days to vote on the bill. Over 200 crypto firms, including Coinbase, Ripple, and Kraken, have urged the Senate to pass the CLARITY Act, emphasizing the need for clear regulatory frameworks to foster domestic innovation.

    However, uncertainties persist. Reports suggesting Ripple has committed $1 million directly to John Deaton’s 2026 Senate campaign, and claims of Ripple CTO David Schwartz donating XRP to Deaton’s campaign, remain unconfirmed by public campaign finance records. Additionally, the passage of the CLARITY Act before the August recess is not guaranteed.

    Ripple’s substantial political spending appears to align with its broader investments in institutional finance, encompassing services like RLUSD and custody, alongside acquisitions. This strategic alignment suggests that achieving regulatory clarity is a key business priority for the company, extending beyond specific token-related objectives.

    Critics have voiced concerns regarding the concentration of crypto’s political influence, noting its significant share of corporate election spending. The industry, in response, points to similar long-standing political strategies employed by sectors such as banking, energy, and pharmaceuticals. The outcome of the CLARITY Act vote and the ongoing evolution of the crypto industry’s political engagement will be closely monitored.

    Why This Matters

    The materials describe a narrow update: Crypto companies, notably Ripple, have become major political donors in the US, contributing tens of millions of dollars through entities like Fairshake to influence elections and legislation. Whether Ripple has committed $1 million directly to John Deaton’s 2026 Senate campaign.

    Broader Context

    Source materials place the factual news in this context: Ripple has become one of the largest corporate political donors in the United States this election cycle, while the market structure bill backed by the crypto industry remains before the Senate ahead of the August recess.

  • Bybit Supports Injective Network Upgrade

    Bybit Supports Injective Network Upgrade

    Bybit to Support Injective Network Upgrade, Deposit and Withdrawal Services to be Temporarily Halted

    Bybit has announced its support for the upcoming Injective (INJ) v1.20.3 network upgrade. The upgrade is scheduled to occur on July 29, 2026, at approximately 11:30 AM UTC, or at block height 176,273,000.

    To facilitate a seamless transition, Bybit will temporarily suspend deposit and withdrawal services for Injective (INJ) starting at 11:00 AM UTC on July 29, 2026. Trading activities, however, will remain unaffected during this period.

    The exchange has stated that there will be no further announcements regarding the resumption of deposit and withdrawal services. Users wishing to be notified when these services are back online are advised to visit the Deposit or Withdrawal page and activate the “Set Alert” function.

    Further details regarding the Injective network upgrade can be found in the official release notes.

  • Securitize Capital’s SEC Registration Enhances Institutional Capabilities Amidst Market Revenue Assessment

    Securitize Capital’s SEC Registration Enhances Institutional Capabilities Amidst Market Revenue Assessment

    Securitize Capital, the advisory subsidiary of the tokenized asset platform Securitize, has registered with the U.S. Securities and Exchange Commission (SEC) as a full investment adviser. This regulatory upgrade, reported on Monday, removes previous constraints on the firm’s ability to serve a wider range of institutional clients and manage diverse asset types within onchain capital markets. However, whether this new status will translate into new Assets Under Management (AUM) inflows or an expanded mandate scope in the near term remains an open question.

    Previously operating as an exempt reporting adviser, Securitize Capital was subject to limitations that restricted its scope. The transition to a full Registered Investment Adviser (RIA) status under the Investment Advisers Act of 1940 imposes additional disclosure, compliance, recordkeeping, and examination requirements. Crucially, it also empowers the firm to pursue a broader array of institutional advisory mandates, separately managed accounts, and formal investment strategies leveraging its tokenization infrastructure.

    This move is seen as a significant step in completing Securitize’s U.S. regulatory stack. The firm already operates an SEC-registered broker-dealer, an alternative trading system, a transfer agent, and fund administration services, positioning it as a vertically integrated infrastructure provider for tokenized securities. This comprehensive regulatory framework is a configuration few competitors can currently match, according to Securitize.

    The practical effect of this registration is that Securitize Capital can now engage with a wider spectrum of institutional clients and manage a more diverse set of assets, without the caps previously imposed by its exempt status. This is particularly relevant for institutional asset managers already utilizing Securitize’s platform for tokenized funds, as the full RIA status is expected to reduce friction in adding advisory services to existing relationships.

    Securitize, which began trading on the New York Stock Exchange under the ticker SECZ on July 2 following a merger with Cantor Equity Partners II, currently manages approximately $4.8 billion in tokenized assets across funds overseen by institutional asset managers. Despite this operational scale, Securitize shares have seen a decline of roughly 46% from their first-day closing price. This stock performance context highlights that as a public company with earnings obligations, the advisory license needs to translate into fee-generating mandates to justify the increased regulatory overhead.

    The market is reportedly still assessing the revenue model tied to Securitize’s infrastructure. While the infrastructure itself is considered compelling, the ultimate success of this regulatory enhancement will hinge on its ability to drive new AUM inflows and expand mandate scope in the near term. Whether this translates into tangible revenue growth remains an open question that the registration itself does not immediately answer.

    This development aligns with broader trends in institutional crypto infrastructure, where firms like Ripple and Fasanara Capital are also expanding their offerings for institutional finance. The pattern suggests that traditional capital is increasingly committing to onchain markets, even without perfect regulatory clarity. Securitize’s enhanced regulatory standing strengthens its position to capitalize on this trend, offering a regulated pathway for institutional participation in tokenized securities.

    Why This Matters

    The materials describe a narrow update: Securitize Capital, previously an exempt reporting adviser, has now registered as a full investment adviser with the SEC. Whether the new RIA status will convert into new AUM inflows or an expanded mandate scope in the near term.

    Broader Context

    Source materials place the factual news in this context: The move graduates the firm from exempt reporting adviser status, under which it operated with constraints that limited the scope of the assets and clients it could serve.

  • GIGADEVICEUSDT Perpetual Contract Launches with 25x Leverage

    GIGADEVICEUSDT Perpetual Contract Launches with 25x Leverage

    Bybit Launches GIGADEVICEUSDT Perpetual Contract

    Cryptocurrency exchange Bybit has announced the listing of the GIGADEVICEUSDT Perpetual Contract, with trading now live. The new contract offers users leverage of up to 25x.

    The GIGADEVICEUSDT Perpetual Contract is also accessible through Bybit’s Futures bots, including Futures Grid, Futures Martingale, and Futures Combo.

    Contract Details:

    • Contract Type: USDT Perpetual Contract
    • Underlying Asset: GigaDevice (GIGADEVICE)
    • Settlement Asset: USDT
    • Tick Size: 0.01
    • Maximum Leverage: 25x
    • Capped Funding Rate: 2%
    • Funding Fee Settlement Interval: Every 8 hours
    • Trading Hours: 24/7

    Official Information:

  • Cartoonist Sues AI Meme Generator Over Copyrighted Comic Strip Template

    Cartoonist Sues AI Meme Generator Over Copyrighted Comic Strip Template

    A Filipino cartoonist has filed a lawsuit against an AI-powered advertising generator, alleging the company sold access to his copyrighted comic strip as a template for paying subscribers. The complaint, lodged by Elmer Saflor, known online as ‘Superelmer,’ against Memes.ai (Memes Apps), marks a new front in legal battles over AI and creative content, distinct from disputes focused on AI training data.

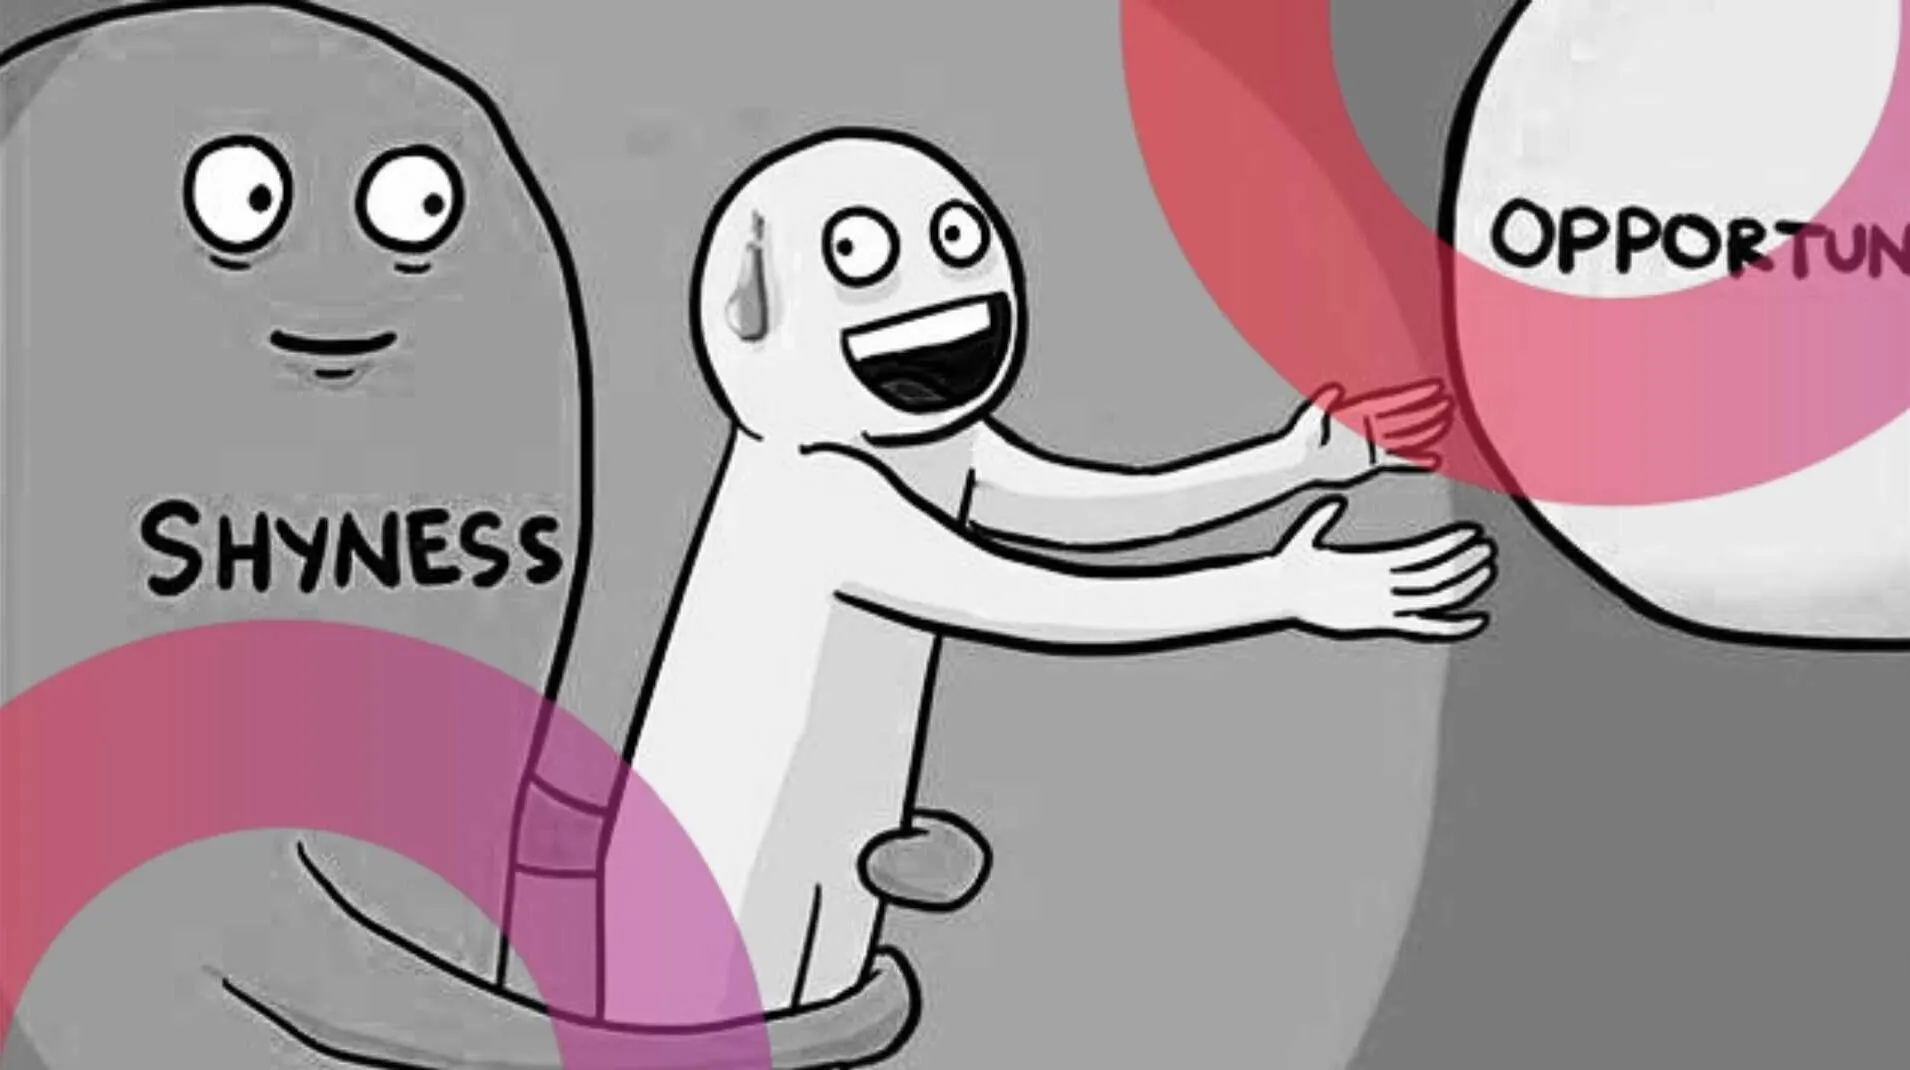
    Saflor’s lawsuit, filed on July 1, 2024, in the Central District of California, claims that Memes.ai offered his comic strip, ‘Running Away Balloon,’ to its subscribers as an advertising template. The original comic, which depicts a stick figure reaching for ‘opportunities’ while being held back by ‘shyness,’ was first posted to Facebook in April 2017. Saflor registered the copyright for the work in 2024.

    Memes.ai operates as an AI ad generator with subscription plans ranging from $40 to $199 per month. The company markets its services to brands, agencies, and marketers, with its website stating that generated ads are for customer business use, including paid advertising. According to the complaint, Saflor alleges that Memes.ai made his artwork available in its template library, searchable by subscribers.

    A New Legal Frontier: Beyond AI Training Data

    Unlike recent high-profile lawsuits against AI firms such as Stability AI and Midjourney, which have primarily centered on whether ingesting works to train AI models constitutes fair use, Saflor’s complaint focuses on ordinary reproduction and public display infringement. The lawsuit reportedly leans on the company’s own marketing materials to argue that the infringement was willful. Saflor is seeking a permanent injunction to stop the alleged use, an accounting of profits, disgorgement of those profits, and statutory damages.

    Under the Copyright Act, statutory damages for willful infringement can be capped at $150,000 per work. Saflor’s broader goal, according to reports, is to use the case to push for discovery and raise questions about how AI-powered platforms utilize creators’ work for commercial purposes.

    Potential Implications and Expert Views

    Internet law scholar Eric Goldman has commented on the potential reach of a ruling against Memes.ai, suggesting that targeting the supplier rather than the advertiser could create significant legal complexities. The case also comes in the wake of a 2024 federal appeals court ruling that found a political campaign infringed on the ‘Success Kid’ meme, indicating a shifting legal landscape for meme usage in commercial and political contexts.

    Saflor’s filing does not address the issue of AI model training fair use. Instead, it targets the direct commercial offering of his specific artwork as a template. The outcome of this lawsuit could have implications for other AI meme generators and how they commercialize creative assets, potentially raising broader questions about creator rights and platform responsibilities in the evolving AI landscape. The uncertainties surrounding the case include whether Memes.ai’s use constitutes ordinary infringement, the extent of its impact on other meme generators, and the final resolution of Saflor’s claims for damages and broader legal questions.

    Broader Context

    Source materials place the factual news in this context: The lawsuit is filed against Memes.ai, an AI ad generator.

  • Portfolio Margin Collateral Ratio and USDⓈ-M Perpetual Leverage Tiers Update

    Portfolio Margin Collateral Ratio and USDⓈ-M Perpetual Leverage Tiers Update

    Binance to Adjust Portfolio Margin and Futures Leverage Parameters

    Binance announced upcoming adjustments to its Portfolio Margin Pro and USDⓈ-M Perpetual Contracts, set to take effect on July 31, 2026. The changes aim to refine collateral ratios and leverage tiers for various assets.

    Portfolio Margin Updates

    Effective July 31, 2026, at 06:00 (UTC), Binance will update the collateral ratio and tiered collateral ratio for specific assets under Portfolio Margin and Portfolio Margin Pro. These updates are expected to be completed within approximately 30 minutes.

    The following assets under Portfolio Margin will see adjusted collateral ratios:

    • STX: Collateral Ratio changes from 30% to 10%.
    • SANTOS: Collateral Ratio changes from 30% to 10%.
    • EURI: Collateral Ratio changes from 20% to 30%.

    For Portfolio Margin Pro, the following tiered collateral ratios will be adjusted:

    STX

    | Tier | Floor (USD) | Cap (USD) | Collateral Ratio (Before) | Tier | Floor (USD) | Cap (USD) | Collateral Ratio (After) |
    | :— | :———- | :———- | :———————— | :— | :———- | :———- | :———————– |
    | 9 | 0 | 100,000 | 100% | 10 | 0 | 50,000 | 100% |
    | | 100,000 | 250,000 | 80% | | 50,000 | 100,000 | 80% |
    | | 250,000 | 500,000 | 50% | | 100,000 | 200,000 | 50% |
    | | 500,000 | 99,999,999,999 | 10% | | 200,000 | 400,000 | 20% |
    | | | | | | 400,000 | 99,999,999,999 | 10% |

    WBTC

    | Tier | Floor (USD) | Cap (USD) | Collateral Ratio (Before) | Tier | Floor (USD) | Cap (USD) | Collateral Ratio (After) |
    | :— | :———- | :———- | :———————— | :— | :———- | :———- | :———————– |
    | 10 | 0 | 50,000 | 100% | 8 | 0 | 200,000 | 100% |
    | | 50,000 | 100,000 | 80% | | 200,000 | 400,000 | 80% |
    | | 100,000 | 200,000 | 50% | | 400,000 | 800,000 | 70% |
    | | 200,000 | 400,000 | 20% | | 800,000 | 1,000,000 | 40% |
    | | 400,000 | 99,999,999,999 | 10% | | 1,000,000 | 99,999,999,999 | 20% |

    SXT, RUNE, IMX, COMP, BERA, SKL, ENJ, BIO

    | Tier | Floor (USD) | Cap (USD) | Collateral Ratio (Before) | Tier | Floor (USD) | Cap (USD) | Collateral Ratio (After) |
    | :— | :———- | :———- | :———————— | :— | :———- | :———- | :———————– |
    | 10 | 0 | 50,000 | 100% | 9 | 0 | 100,000 | 100% |
    | | 50,000 | 100,000 | 80% | | 100,000 | 250,000 | 80% |
    | | 100,000 | 200,000 | 50% | | 200,000 | 400,000 | 20% |
    | | 200,000 | 400,000 | 20% | | 400,000 | 99,999,999,999 | 10% |
    | | 400,000 | 99,999,999,999 | 10% | | | | N/A |

    Binance Futures Leverage and Margin Tier Adjustments

    In addition to Portfolio Margin changes, Binance Futures will update the leverage and margin tiers for several USDⓈ-M Perpetual Contracts. These updates are scheduled for July 31, 2026, at 06:30 (UTC) and are expected to be completed within approximately one hour.

    Important Note: Existing positions opened before these updates will be affected. Futures running grid strategies may expire due to these changes, and users are advised to adjust their positions accordingly.

    STXUSDT (USDⓈ-M Perpetual Contract)

    | Leverage Before Change | Position Before Change (Notional Value in USDT) | Maintenance Margin Rate Before Change | Leverage After Change | Position After Change (Notional Value in USDT) | Maintenance Margin Rate After Change |
    | :——————— | :———————————————- | :———————————- | :——————– | :——————————————— | :———————————– |
    | 51 – 75x | 0 < Position ≤ 5,000 | 1.00% | 51 – 75x | 0 < Position ≤ 5,000 | 1.00% |
    | 26 – 50x | 5,000 < Position ≤ 10,000 | 1.50% | 26 – 50x | 5,000 < Position ≤ 10,000 | 1.50% |
    | 21 – 25x | 10,000 < Position ≤ 50,000 | 2.00% | 21 – 25x | 10,000 < Position ≤ 25,000 | 2.00% |
    | 16 – 20x | 50,000 < Position ≤ 100,000 | 2.50% | 11 – 20x | 25,000 < Position ≤ 50,000 | 2.50% |
    | 11 – 15x | 100,000 < Position ≤ 175,000 | 3.33% | NA | | |
    | 6 – 10x | 175,000 < Position ≤ 250,000 | 5.00% | 6 – 10x | 50,000 < Position ≤ 125,000 | 5.00% |
    | 5x | 250,000 < Position ≤ 750,000 | 10.00% | 5x | 125,000 < Position ≤ 250,000 | 10.00% |
    | 4x | 750,000 < Position ≤ 1,500,000 | 12.50% | 4x | 250,000 < Position ≤ 500,000 | 12.50% |
    | 3x | 1,500,000 < Position ≤ 4,500,000 | 16.67% | 3x | 500,000 < Position ≤ 1,000,000 | 16.67% |
    | 2x | 4,500,000 < Position ≤ 7,500,000 | 25.00% | 2x | 1,000,000 < Position ≤ 7,500,000 | 25.00% |
    | 1x | 7,500,000 < Position ≤ 12,000,000 | 50.00% | 1x | 7,500,000 < Position ≤ 12,500,000 | 50.00% |

    CHRUSDT, IDOLUSDT, HIVEUSDT, STEEMUSDT, CTKUSDT, and WAXPUSDT (USDⓈ-M Perpetual Contracts)

    | Leverage Before Change | Position Before Change (Notional Value in USDT) | Maintenance Margin Rate Before Change | Leverage After Change | Position After Change (Notional Value in USDT) | Maintenance Margin Rate After Change |
    | :——————— | :———————————————- | :———————————- | :——————– | :——————————————— | :———————————– |
    | 21 – 50x | 0 < Position ≤ 5,000 | 1.50% | 21 – 25x | 0 < Position ≤ 5,000 | 2.00% |
    | 11 – 20x | 5,000 < Position ≤ 10,000 | 2.50% | 11 – 20x | 5,000 < Position ≤ 10,000 | 2.50% |
    | 6 – 10x | 10,000 < Position ≤ 20,000 | 5.00% | 6 – 10x | 10,000 < Position ≤ 20,000 | 5.00% |
    | 5x | 20,000 < Position ≤ 50,000 | 10.00% | 5x | 20,000 < Position ≤ 50,000 | 10.00% |
    | 4x | 50,000 < Position ≤ 250,000 | 12.50% | 4x | 50,000 < Position ≤ 100,000 | 12.50% |
    | 3x | 250,000 < Position ≤ 500,000 | 16.67% | 3x | 100,000 < Position ≤ 250,000 | 16.67% |
    | 2x | 500,000 < Position ≤ 7,500,000 | 25.00% | 2x | 250,000 < Position ≤ 2,500,000 | 25.00% |
    | 1x | 7,500,000 < Position ≤ 12,500,000 | 50.00% | 1x | 2,500,000 < Position ≤ 5,000,000 | 50.00% |

    ICXUSDT, CETUSUSDT, BREVUSDT, METISUSDT, CTSIUSDT, ILVUSDT, and COTIUSDT (USDⓈ-M Perpetual Contracts)

    | Leverage Before Change | Position Before Change (Notional Value in USDT) | Maintenance Margin Rate Before Change | Leverage After Change | Position After Change (Notional Value in USDT) | Maintenance Margin Rate After Change |
    | :——————— | :———————————————- | :———————————- | :——————– | :——————————————— | :———————————– |
    | 26 – 50x | 0 < Position ≤ 5,000 | 1.50% | 21 – 50x | 0 < Position ≤ 5,000 | 1.50% |
    | 21 – 25x | 5,000 < Position ≤ 10,000 | 2.00% | NA | | |
    | 11 – 20x | 10,000 < Position ≤ 25,000 | 2.50% | 11 – 20x | 5,000 < Position ≤ 10,000 | 2.50% |
    | 6 – 10x | 25,000 < Position ≤ 62,500 | 5.00% | 6 – 10x | 10,000 < Position ≤ 20,000 | 5.00% |
    | 5x | 62,500 < Position ≤ 125,000 | 10.00% | 5x | 20,000 < Position ≤ 50,000 | 10.00% |
    | 4x | 125,000 < Position ≤ 250,000 | 12.50% | 4x | 50,000 < Position ≤ 250,000 | 12.50% |
    | 3x | 250,000 < Position ≤ 500,000 | 16.67% | 3x | 250,000 < Position ≤ 500,000 | 16.67% |
    | 2x | 500,000 < Position ≤ 7,500,000 | 25.00% | 2x | 500,000 < Position ≤ 7,500,000 | 25.00% |
    | 1x | 7,500,000 < Position ≤ 12,500,000 | 50.00% | 1x | 7,500,000 < Position ≤ 12,500,000 | 50.00% |

    MOVEUSDT (USDⓈ-M Perpetual Contract)

    | Leverage Before Change | Position Before Change (Notional Value in USDT) | Maintenance Margin Rate Before Change | Leverage After Change | Position After Change (Notional Value in USDT) | Maintenance Margin Rate After Change |
    | :——————— | :———————————————- | :———————————- | :——————– | :——————————————— | :———————————– |
    | 21 – 50x | 0 < Position ≤ 5,000 | 1.50% | 21 – 25x | 0 < Position ≤ 5,000 | 2.00% |
    | 11 – 20x | 5,000 < Position ≤ 10,000 | 2.50% | 11 – 20x | 5,000 < Position ≤ 10,000 | 2.50% |
    | 6 – 10x | 10,000 < Position ≤ 20,000 | 5.00% | 6 – 10x | 10,000 < Position ≤ 20,000 | 5.00% |
    | 5x | 20,000 < Position ≤ 50,000 | 10.00% | 5x | 20,000 < Position ≤ 50,000 | 10.00% |
    | 4x | 50,000 < Position ≤ 250,000 | 12.50% | 4x | 50,000 < Position ≤ 100,000 | 12.50% |
    | 3x | 250,000 < Position ≤ 500,000 | 16.67% | 3x | 100,000 < Position ≤ 250,000 | 16.67% |
    | 2x | 500,000 < Position ≤ 7,500,000 | 25.00% | 2x | 250,000 < Position ≤ 2,500,000 | 25.00% |
    | 1x | 7,500,000 < Position ≤ 12,500,000 | 50.00% | 1x | 2,500,000 < Position ≤ 5,000,000 | 50.00% |

    STORJUSDT (USDⓈ-M Perpetual Contract)

    | Leverage Before Change | Position Before Change (Notional Value in USDT) | Maintenance Margin Rate Before Change | Leverage After Change | Position After Change (Notional Value in USDT) | Maintenance Margin Rate After Change |
    | :——————— | :———————————————- | :———————————- | :——————– | :——————————————— | :———————————– |
    | 26 – 50x | 0 < Position ≤ 5,000 | 1.50% | NA | | |
    | 21 – 25x | 5,000 < Position ≤ 10,000 | 2.00% | 21 – 25x | 0 < Position ≤ 5,000 | 2.00% |
    | 11 – 20x | 10,000 < Position ≤ 25,000 | 2.50% | 11 – 20x | 5,000 < Position ≤ 10,000 | 2.50% |
    | 6 – 10x | 25,000 < Position ≤ 62,500 | 5.00% | 6 – 10x | 10,000 < Position ≤ 20,000 | 5.00% |
    | 5x | 62,500 < Position ≤ 125,000 | 10.00% | 5x | 20,000 < Position ≤ 50,000 | 10.00% |
    | 4x | 125,000 < Position ≤ 250,000 | 12.50% | 4x | 50,000 < Position ≤ 100,000 | 12.50% |
    | 3x | 250,000 < Position ≤ 500,000 | 16.67% | 3x | 100,000 < Position ≤ 250,000 | 16.67% |
    | 2x | 500,000 < Position ≤ 7,500,000 | 25.00% | 2x | 250,000 < Position ≤ 2,500,000 | 25.00% |
    | 1x | 7,500,000 < Position ≤ 12,500,000 | 50.00% | 1x | 2,500,000 < Position ≤ 5,000,000 | 50.00% |

    BOTUSDT, WENUSDT, SHAZUSDT, and PENGUSDT (USDⓈ-M Perpetual Contracts)

    | Leverage Before Change | Position Before Change (Notional Value in USDT) | Maintenance Margin Rate Before Change | Leverage After Change | Position After Change (Notional Value in USDT) | Maintenance Margin Rate After Change |
    | :——————— | :———————————————- | :———————————- | :——————– | :——————————————— | :———————————– |
    | 21 – 25x | 0 < Position ≤ 250,000 | 2.00% | NA | | |
    | 16 – 20x | 250,000 < Position ≤ 1,000,000 | 2.50% | 11 – 20x | 0 < Position ≤ 200,000 | 2.50% |
    | 11 – 15x | 1,000,000 < Position ≤ 2,000,000 | 3.33% | NA | | |
    | 6 – 10x | 2,000,000 < Position ≤ 5,000,000 | 5.00% | 6 – 10x | 200,000 < Position ≤ 400,000 | 5.00% |
    | 5x | 5,000,000 < Position ≤ 8,000,000 | 10.00% | 5x | 400,000 < Position ≤ 1,000,000 | 10.00% |
    | 4x | 8,000,000 < Position ≤ 15,000,000 | 12.50% | 4x | 1,000,000 < Position ≤ 1,500,000 | 12.50% |
    | 3x | 15,000,000 < Position ≤ 25,000,000 | 16.67% | 3x | 1,500,000 < Position ≤ 5,000,000 | 16.67% |
    | 2x | 25,000,000 < Position ≤ 50,000,000 | 25.00% | 2x | 5,000,000 < Position ≤ 7,500,000 | 25.00% |
    | 1x | 50,000,000 < Position ≤ 200,000,000 | 50.00% | 1x | 7,500,000 < Position ≤ 12,500,000 | 50.00% |

    Users are advised to monitor their Unified Maintenance Margin Ratio (uniMMR) closely, as changes in collateral ratios can impact it and potentially lead to liquidation or losses.