Tag: Regulation & Policy

  • Fairshake Endorses 32 House Candidates Amid Crypto Spending Surge

    Fairshake Endorses 32 House Candidates Amid Crypto Spending Surge

    Crypto’s Political Powerhouse Targets House Races

    Fairshake, the cryptocurrency industry’s largest political spending network, is launching a significant push into the general election with a broad campaign targeting U.S. House candidates ahead of the November midterms. The organization has identified 32 incumbent lawmakers it plans to support, a slate that is notably bipartisan, comprising 19 Republicans and 13 Democrats.

    Multi-Million Dollar Investment in Key Races

    The initial phase of Fairshake’s campaign involves a substantial financial commitment, with six races each slated to receive $1 million in independent expenditures. This brings the disclosed initial investment to at least $6 million. These six races are evenly split between the two major parties.

    Bipartisan Support Driven by Crypto Policy

    The candidates receiving the largest financial backing from Fairshake are Democrats Janelle Bynum, Steven Horsford, and Derek Tran, alongside Republicans French Hill, Bill Huizenga, and Bryan Steil. The broader list of 32 supported candidates also reflects this bipartisan approach. The unifying factor among these lawmakers is not their party affiliation, but rather their voting records on digital asset legislation. All 32 candidates have backed the House CLARITY market-structure bill, a key priority for the cryptocurrency sector.

    This focus provides Fairshake with a clear objective: to support lawmakers who have championed the regulatory framework the crypto industry seeks to advance.

    Independent Spending, Not Direct Donations

    It is important to note the operational mechanics of Fairshake’s support. The organization functions as a super PAC, meaning its expenditures are made independently of candidate campaigns and are not transferred directly into their accounts. This independent spending can be used for advertising and other electioneering activities aimed at supporting or opposing candidates. While substantial, this is distinct from candidates directly receiving large sums of money.

    The scale of this investment underscores the growing entanglement of cryptocurrency policy with electoral strategy. Major players within the industry have channeled significant funds into Fairshake and affiliated groups, recognizing that congressional votes can profoundly influence the progression of legislation concerning market structure, stablecoins, and securities.

    The upcoming election results will represent only the initial benchmark. The subsequent challenge will be to determine whether a pro-crypto bloc that emerges from the November elections can translate political backing into tangible legislative progress when the next Congress convenes.
  • CFTC Seeks Public Input on Crypto Exchange Regulation Plan, Outlining Potential Framework

    CFTC Seeks Public Input on Crypto Exchange Regulation Plan, Outlining Potential Framework

    The U.S. Commodity Futures Trading Commission (CFTC) has initiated a 60-day public comment period for its newly released plan aimed at regulating cryptocurrency exchanges. This move signifies a formal step towards establishing federal guidelines for the digital asset industry, with the agency seeking input before drafting concrete rules.

    The CFTC’s plan, published on October 5, 2026, outlines a proposal for a federal license for crypto exchanges. The agency’s stated goals are to prevent fraud and provide clearer regulatory pathways for businesses operating in the cryptocurrency space. This initiative comes weeks after the Clarity Act, a previous legislative attempt to regulate digital assets, failed to pass the Senate.

    Regulatory Process and Public Comment

    According to the CFTC’s plan, the public will have 60 days from its publication in the Federal Register to submit comments. This period is crucial for shaping the final regulations. The agency’s approach is designed to address issues such as the fraud seen in cases like FTX, by establishing preventative measures rather than solely relying on post-event enforcement actions. The notice also appears to reframe past CFTC actions against entities like Kraken, Ooki DAO, and Uniswap as “regulation by enforcement,” suggesting a shift towards a more proactive and defined regulatory framework.

    Potential Implications and Industry Context

    Proponents suggest that a federal license could allow U.S. exchanges to offer leveraged products, which are currently restricted. This could pave the way for a more robust onshore market for perpetual futures. Furthermore, clear regulatory guidance is expected to simplify engagement with the crypto market for traditional financial institutions such as banks and brokers, who have historically faced uncertainty regarding which regulator has jurisdiction. The author suggests that this increased clarity could lead to easier onboarding for users, potentially driving user growth and broader industry expansion.

    Uncertainties Remain

    However, significant uncertainties remain. The specific details of the rules that may ultimately be drafted are not yet known, as the current document is a proposal open for public input. The ultimate impact on asset prices is also uncertain, with the possibility of gains for some assets but not necessarily all. The plan itself is a step in a process, and its final form and effectiveness are yet to be determined.

    This regulatory initiative by the CFTC represents a notable development in the ongoing effort to establish a comprehensive framework for the cryptocurrency industry in the United States. The agency’s call for public comment underscores the importance of stakeholder input in shaping future regulations. The outcome of this comment period and the subsequent rule-making process will be closely watched by investors, industry professionals, and policymakers alike.

    Why This Matters

    The materials describe a narrow update: The CFTC has published a plan to regulate crypto exchanges, which includes a proposal for a federal license. The specific details of the drafted rules are not yet known.

  • Hong Kong to Introduce Licensing for Four Virtual Asset Business Types by End-2026

    Hong Kong to Introduce Licensing for Four Virtual Asset Business Types by End-2026

    The Hong Kong government is set to introduce a bill by the end of 2026 that may establish licensing requirements for four key types of virtual asset businesses: dealing, custody, advisory, and management. This initiative represents a significant expansion of the city’s regulatory oversight for the digital asset sector.

    Secretary for Financial Services and the Treasury Christopher Hui reported the end-2026 target for submitting the bill to the Legislative Council on October 5, 2026. The proposed legislation is a joint effort by the Financial Services and the Treasury Bureau (FSTB) and the Securities and Futures Commission (SFC), with the SFC designated as the primary supervisory authority for these new licensing regimes.

    The new framework aims to regulate virtual asset dealing, custody, advisory, and management services under the guiding principle of “same business, same risks, same rules.” This approach mirrors the existing Securities and Futures Ordinance, ensuring that each new virtual asset license category aligns with a corresponding type under the established ordinance.

    This move is part of Hong Kong’s broader 2026-2030 financial market development strategy and aligns with the government’s Policy Statement 2.0 on Digital Assets. Public consultations on the proposed regimes have already been conducted. Conclusions from consultations concerning dealing and custody services, which garnered over 190 responses, were published on December 24, 2025. Separately, conclusions from consultations on advisory and management services were released on May 26, 2026, following 51 responses.

    A critical aspect of the proposal is the absence of transitional or grandfathering provisions. Consequently, businesses currently operating in these four virtual asset sectors that do not already possess licenses from the SFC or the Hong Kong Monetary Authority (HKMA) may be required to cease operations once the new regulations come into effect.

    This planned legislation builds on Hong Kong’s recent regulatory actions in the virtual asset space. The licensing of virtual asset trading platforms commenced in 2023, bringing centralized exchanges under SFC supervision. The Stablecoins Ordinance also took effect on August 1, 2025. The forthcoming bill extends this regulatory reach to over-the-counter (OTC) desks, custodians, advisers, and managers, encompassing areas that have previously operated outside the city’s primary crypto regulatory framework.

    The SFC will oversee the implementation and enforcement of the four licensing regimes, ensuring compliance with the evolving virtual asset regulations.

    Why This Matters

    The materials describe a narrow update: The Hong Kong government plans to submit a bill to the Legislative Council by the end of 2026 to license four types of virtual asset businesses: dealing, custody, advisory, and management. The bill extends oversight into areas that have so far sat outside the city’s main crypto framework.

    Broader Context

    Source materials place the factual news in this context: The guiding philosophy is “same business, same risks, same rules.”.

  • FinCEN Scraps Crypto Wallet and Mixer Rules

    FinCEN Scraps Crypto Wallet and Mixer Rules

    FinCEN Scraps Proposed Rules on Self-Custody Wallets and Crypto Mixers

    The Financial Crimes Enforcement Network (FinCEN) on Monday rescinded two proposed rules, one concerning self-custody cryptocurrency wallets and another targeting crypto mixers.

    In its decision, the Treasury bureau cited the Trump administration’s “deregulatory agenda” as the reason for ending the proposed rule on wallets, which had been pending since December 2020.

    The first withdrawn rule, published on December 23, 2020, aimed to regulate what it termed “unhosted wallets”—those where users manage their own transactions without the involvement of a bank or other financial institution. Under the proposal, banks and money service businesses would have been required to file reports and verify customer identities when a counterparty used such a wallet for a transfer exceeding $10,000, or if multiple transfers summed to over $10,000 within a 24-hour period. Record-keeping requirements would have commenced at $3,000, and the rule also encompassed wallets held at foreign institutions outside the purview of the Bank Secrecy Act, in jurisdictions specified by the agency.

    The second proposal, originating in 2023, sought to impose special measures on crypto mixing services. These services blend coins from multiple users, making it more difficult to trace their origins. The proposal was based on a finding under section 311 of the USA PATRIOT Act, which identified international crypto mixing as a class of transactions of primary concern for money laundering. Had it been enacted, the rule would have mandated that covered financial institutions report any transaction they knew or suspected involved mixing with a foreign link. This would have included details such as amounts, wallet addresses, transaction hashes, and IP addresses, along with maintaining records of each customer’s full identity.

    Deputy Director Jimmy L. Kirby signed the notice for the wallet rule withdrawal, stating the bureau would take no further action and referencing a July 2025 White House report from the President’s Working Group on Digital Asset Markets. FinCEN indicated it had considered public comments submitted on both proposals before deciding to withdraw them.

    The Crypto Council for Innovation (CCI), an industry group that had submitted comments on the mixing proposal, described both withdrawals as “positive for the digital asset ecosystem” in a post on X. The CCI had previously warned that the proposal’s broad definition of mixing could inadvertently encompass legitimate activities and characterized the outcome as “the rulemaking process working.” Regarding the wallet rule, the CCI argued that its withdrawal would help prevent regulators from prohibiting or restricting the use of self-hosted wallets.

    These decisions come at a time when privacy-focused crypto services are facing increased legal scrutiny. For instance, Samourai Wallet co-founders Keonne Rodriguez and William Lonergan Hill have agreed to plead guilty in connection with their mixing service. Prosecutors allege the wallet processed over $2 billion in illicit transactions and laundered more than $100 million. The founders’ legal team had sought dismissal of charges following an April 2025 Justice Department memo suggesting prosecutors would no longer pursue cases based solely on user actions or regulatory technicalities. They also alleged that officials withheld internal FinCEN communications that indicated Samourai was not considered a money transmitter.

    Rodriguez and Hill were subsequently sentenced to five and four years in prison, respectively. During Rodriguez’s sentencing, the judge remarked that he had “used his talent to enable fraud.” Supporters, including analyst Kyle Chasse, maintain that the platform was designed to facilitate anonymous cryptocurrency transfers rather than to conceal illicit activities.

  • CFTC Unveils New Crypto Market Rules

    CFTC Unveils New Crypto Market Rules

    CFTC Unveils Proposed Rules for Crypto Trading and Markets

    The U.S. Commodity Futures Trading Commission (CFTC) has officially released comprehensive details regarding the regulation of crypto asset transactions and markets. The proposed framework aims to provide clearer directives for the burgeoning digital asset industry.

    Delivery and Self-Custody Clarification

    One key aspect of the proposal addresses the delivery of crypto assets in leveraged or margin trading. Under the new guidelines, retail-financed, leveraged, or margin trading will be considered complete if crypto assets are delivered to a non-custodial wallet within 28 days. This provision is intended to distinguish normal crypto purchases and self-custody from activities requiring more stringent exchange regulation.

    Federal Licensing Option for Crypto Exchanges

    The CFTC is also proposing a new, optional federal licensing system for crypto exchanges. This federal license would allow exchanges to bypass individual state registration requirements. Crucially, it would enable these licensed entities to offer retail margin, leveraged, and financed crypto trading, activities currently prohibited at the state level for spot market trading.

    Framework Details

    The proposals are divided into two main areas:

    • Derivatives and Financing Layer: This framework focuses on regulating retail crypto trading that utilizes borrowed funds, leverage, and margin, operating under Section 2(c)(2)(D) of the Commodity Exchange Act. The agency’s recognition of crypto sent to non-custodial wallets as “actual delivery” within 28 days falls under this section.

    • Market Structure and Platform Registration: This part of the proposal introduces customized, optional federal licenses for crypto exchanges under the CFTC’s Designated Contracts Management (DCM) system. These licenses would necessitate robust operational protections, including proof-of-reserves audits, anti-money laundering safeguards, and mandatory intermediation by commission-registered merchants. The primary benefit for exchanges would be the ability to operate under a single federal registration, avoiding the complexities of state-by-state compliance, and the authorization to offer leveraged and financed trading to retail customers.

    Oversight and Public Comment

    While the federal and state licensing structures offer different benefits, the CFTC would maintain ultimate oversight across the entire system. Following the publication of the proposals in the Federal Register, stakeholders, industry participants, and the public will have a 60-day period to submit comments.

    Industry Reaction and Caution

    The CFTC’s move is seen as a positive step towards regulatory clarity for the crypto sector. However, industry lawyers have cautioned that the proposed guidelines may lack permanence and could be subject to changes with shifts in agency or presidential administrations.

  • OKX and ICE File with SEC for Tokenized Stock Trading Exchange

    OKX and ICE File with SEC for Tokenized Stock Trading Exchange

    OKXICE LLC, a joint venture between cryptocurrency exchange OKX and Intercontinental Exchange (ICE), has filed with the U.S. Securities and Exchange Commission (SEC) to establish a regulated exchange for trading tokenized U.S. stocks. The initial offering is expected to include 63 companies listed on the New York Stock Exchange (NYSE).

    The filing, which occurred on October 4, aims to allow for the trading of tokenized versions of U.S. equities. Companies whose stocks are selected for tokenization will have a 30-day period to opt out before trading can commence. This venture combines OKX’s blockchain infrastructure with ICE’s market technology.

    According to a report by Bloomberg, the SEC introduced its temporary Innovation Exemption in September. This exemption permits certain tokenized securities venues to facilitate secondary trading of tokenized U.S. stocks through permissioned automated makers and liquidity pools, provided specific conditions are met. These conditions include that tokenized shares must carry the same shareholder rights as the underlying securities, smart contracts must be auditable and run on public, permissionless blockchains, and trading must cease if the underlying stock is suspended on its primary exchange.

    As CryptoPotato reported, Coinbase had previously announced in June plans to offer tokenized stocks to customers outside the U.S., with shares backed 1:1 by the underlying assets and carrying shareholder rights. This move predated the SEC’s September exemption and indicated a growing trend among crypto exchanges to explore connections with stock trading infrastructure.

    The filing by OKXICE LLC represents one of the first attempts by a crypto exchange to offer tokenized U.S. stocks through a regulated exchange under the SEC’s temporary regulations. The partnership with ICE, which acquired a stake in OKX in March, provides a foundation for combining exchange infrastructure with blockchain-based trading. This framework could potentially enable round-the-clock trading of U.S.-listed stocks, subject to the SEC’s stipulated conditions.

    However, the launch of OKX’s tokenized stock trading platform is contingent on regulatory processes and the decision of the 63 NYSE-listed companies to participate. The exact date of the launch remains uncertain, depending on the completion of the 30-day notice period and other requirements outlined by the SEC. Whether these companies will opt out of the tokenized stock trading remains a key uncertainty.

    Why This Matters

    The materials describe a narrow update: OKXICE LLC, a joint venture between OKX and ICE, has filed with the SEC to establish a regulated exchange for trading tokenized US stocks. Whether the 63 NYSE-listed companies will opt out of the tokenized stock trading.

    Broader Context

    Source materials place the factual news in this context: The SEC introduced its temporary Innovation Exemption in September, allowing certain tokenized securities venues to facilitate secondary trading of tokenized US stocks through permissioned automated makers and liquidity pools.

  • CFTC Offers Limited-Time Regulatory Path for Crypto Futures to Become True Perpetuals

    CFTC Offers Limited-Time Regulatory Path for Crypto Futures to Become True Perpetuals

    A narrow regulatory window, expiring June 30, 2026, now allows U.S. exchanges to convert existing perpetual-style crypto futures contracts into true perpetuals, provided specific conditions are met. The CFTC’s Division of Market Oversight issued Staff Letter No. 26-19 on June 12, 2026, granting conditional no-action relief to designated contract markets (DCMs).

    This guidance permits DCMs to remove expiration dates from qualifying digital commodity futures contracts, effectively transforming them into true perpetual futures. A no-action letter signifies that the CFTC staff will not recommend enforcement action if certain conditions are followed. This move is not a new rule but rather a written assurance that specific actions will not draw regulatory scrutiny under the outlined circumstances.

    Expedited Conversion Pathway
    The primary benefit of this relief is speed. Ordinarily, altering contract terms can trigger self-certification timing requirements under CFTC Regulation 40.6. Staff Letter No. 26-19 allows DCMs to bypass these usual delays by dropping expiration dates. This action was prompted by requests from Bitnomial Exchange, LLC, and Coinbase Derivatives, LLC, which sought relief for 16 and 22 contracts, respectively.

    Conditions and Eligibility
    However, the relief is conditional. Only contracts tied to digital commodities with “deep, active, and continuous” spot markets are eligible. Bitcoin is cited as a prime example of such an asset. Exchanges must still submit amendments under CFTC Regulation 40.5 or 40.6, certifying compliance before implementing any changes. Furthermore, DCMs are required to solicit market feedback and fulfill risk disclosure obligations.

    Limited Timeframe and Market Impact
    The relief takes effect immediately but expires on June 30, 2026, providing exchanges with a window of under three weeks to act. This limited timeframe suggests a controlled, time-boxed transition rather than an open-ended exemption. Exchanges that miss this window may need to pursue the standard regulatory process.

    This development aligns U.S.-regulated markets with recent CFTC decisions regarding perpetual futures for digital commodities. The approval of KalshiEX LLC’s BTCPERP contract previously set a precedent, making the status of “perpetual-style” contracts with distant expiration dates—some extending up to 25 years—increasingly outdated. Staff Letter No. 26-19 aims to close this gap, allowing exchanges to convert existing products rather than launching entirely new listings.

    For traders, the change offers greater clarity, as a perpetual contract without an expiration date is simpler to understand than one with a distant, regulatory-driven expiry. The eligibility rule is also expected to shape competition, likely concentrating the first wave of true perpetuals around the most established digital commodities, with Bitcoin at the forefront.

    Remaining Uncertainties
    Several uncertainties remain. The exact process Bitnomial and Coinbase Derivatives will employ for contract conversion and how they will handle the required risk disclosures are yet to be detailed. Additionally, it is unclear whether exchanges that do not act before the June 30 deadline will successfully navigate the standard CFTC process.

    Future amendment filings under Regulations 40.5 and 40.6 will provide insight into how quickly exchanges convert their contracts and manage the necessary disclosures.

    Why This Matters

    The materials describe a narrow update: The CFTC’s Division of Market Oversight issued a no-action letter (Staff Letter No. The exact process Bitnomial and Coinbase Derivatives will use to convert their contracts.

    Broader Context

    Source materials place the factual news in this context: The letter aligns US-regulated markets with recent CFTC decisions on how perpetual futures for digital commodities should be treated.

  • CFTC Chair: Commodity Exchange Act Covers Bitcoin

    CFTC Chair: Commodity Exchange Act Covers Bitcoin

    CFTC Chief Argues Existing Law Sufficient for Crypto Regulation

    Washington D.C. – While Congress has grappled for years with how to regulate the burgeoning cryptocurrency market, the head of the Commodity Futures Trading Commission (CFTC) asserted on October 5, 2026, that existing legislation is already adequate. CFTC Chairman Michael S. Selig stated that the Commodity Exchange Act (CEA) has proven effective, and its broad definition of a commodity sufficiently encompasses Bitcoin and the broader digital asset landscape.

    This stance comes as the agency simultaneously unveiled an initial plan for two new rulebooks targeting leveraged cryptocurrency trading platforms.

    Selig articulated his core argument during a keynote address at the Fordham Law Blockchain Regulatory Symposium in New York. He emphasized that the CEA’s expansive definition of commodities naturally includes digital assets. He also highlighted Bitcoin’s established history under the act, noting its classification as a commodity in 2014 paved the way for regulated Bitcoin futures trading in subsequent years. Selig further invoked the “Lindy effect” to discuss Bitcoin, a concept suggesting that the longer something has endured, the greater its likelihood of continued survival.

    CFTC Proposes New Rulebooks for Crypto Trading

    In conjunction with Selig’s remarks, the CFTC released an advance notice of proposed rulemaking for two new regulations: Regulation Crypto Asset Transactions (CTX) and Regulation Crypto Asset Markets (CAM). An advance notice represents the earliest formal stage in the rulemaking process, signaling the agency’s considerations and soliciting public feedback before drafting definitive rules.

    The proposed regulations aim to establish a new registration category termed a “crypto asset market.” This initiative seeks to enhance federal oversight of platforms offering leveraged trading in digital assets. Crucially, these platforms would continue to operate under the existing statutory framework, rather than a completely new legal regime. Proposed safeguards include requirements for proof-of-reserves and measures to combat market manipulation.

    Legislative Efforts Stall, CFTC Turns to Existing Authority

    This move by the CFTC occurs against the backdrop of a stalled legislative effort. A recent attempt in the Senate to advance the Digital Asset Market CLARITY Act failed to pass a cloture vote, falling short by a narrow margin of 49-50. Cloture is a procedural vote required to end debate and advance a bill.

    With Congress unable to pass comprehensive market structure legislation, the CFTC is leveraging its authority under the CEA. Selig’s speech served as a foundational legal and philosophical justification for this approach. The 2014 precedent, which established Bitcoin as a commodity, lends significant weight to this argument. With Bitcoin futures having traded under CFTC supervision for years, Selig is positioning the new proposals as a natural extension of this established track record, rather than a departure into uncharted regulatory territory.

    For leveraged crypto trading venues, these proposals suggest a clearer, albeit potentially more stringent, pathway for operating within the United States. The creation of a dedicated “crypto asset market” registration would provide these platforms with a defined regulatory category.

    Challenges and Future Outlook

    However, significant caveats remain. An advance notice is not a final rule, and the specifics of CTX and CAM could undergo substantial changes following public comment. Furthermore, the durability of rules based on agency interpretation of existing statutes can be subject to legal challenges, unlike legislation enacted by Congress. A future Congress could still introduce market structure legislation that alters or supersedes the CFTC’s current initiatives. The close vote on the CLARITY Act indicates that the broader debate over crypto regulation is far from settled.

    Key developments to monitor include the public comment period on the advance notice, the response of exchanges to the proposed registration category, and any potential regrouping by Senate supporters of the CLARITY Act for future legislative attempts.

  • SEC, CFTC Joint Guidance Classifies 16 Digital Assets as Commodities, Clarifying Regulatory Path

    SEC, CFTC Joint Guidance Classifies 16 Digital Assets as Commodities, Clarifying Regulatory Path

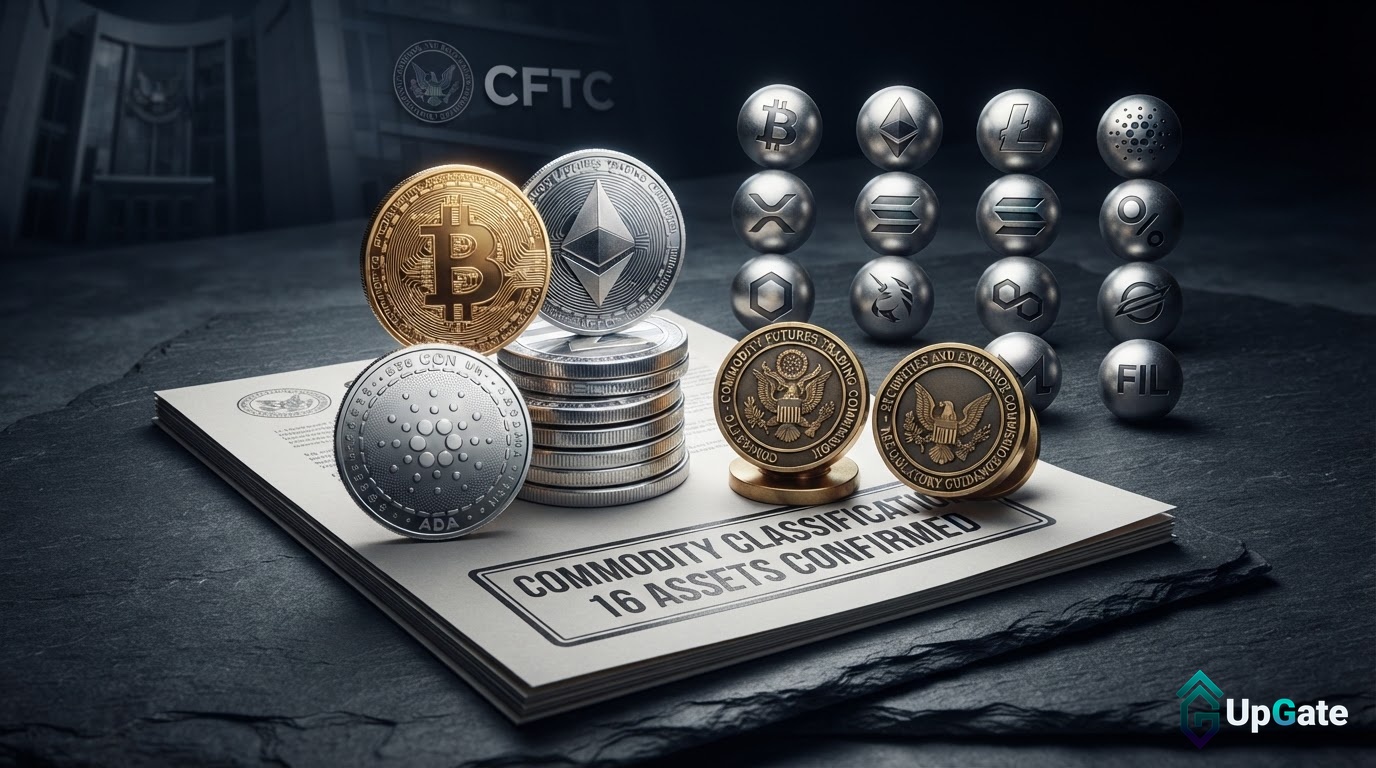
    The U.S. Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC) have jointly issued an interpretive release classifying 16 major digital assets as ‘digital commodities.’ This guidance, unveiled on March 17, 2026, shifts these assets out of the securities classification and places them under the primary oversight of the CFTC in spot markets, according to the guidance. The move clarifies existing law through interpretive rules rather than new legislation, addressing a long-standing debate within the industry.

    Regulatory Landscape Shift

    During a joint presentation, SEC Chairman Paul Atkins and CFTC Chairman Michael S. Selig outlined the guidance, which categorizes digital assets into five groups: digital commodities, digital collectibles, digital tools, stablecoins, and digital securities. Only the last of these buckets is typically treated as a security under U.S. law, according to the guidance. Bitcoin, Ether, Solana, Stellar, Tezos, and XRP were specifically named as digital commodities by the CFTC chairman.

    Context and Precedent

    This classification follows the resolution of significant legal challenges, notably the years-long litigation between Ripple and the SEC over XRP sales. All appeals in that case were dropped in August 2025, and regulators concluded that XRP’s programmatic sales do not constitute securities transactions. The commodity classification for these assets is seen as a direct consequence of this resolution and the agencies’ response to the lack of congressional action on comprehensive digital asset regulation.

    Limitations and Future Outlook

    While digital commodities are now under the CFTC’s anti-fraud and anti-manipulation jurisdiction in spot markets, the guidance emphasizes that this does not mean they are unregulated. Regulators maintain the authority to pursue fraudulent activity across the entire digital asset space. However, the reliance on interpretive rules rather than new legislation introduces inherent uncertainties. Guidance issued by one set of agency heads can be revisited by the next, and comprehensive market structure rules still require congressional action.

    On October 5, 2026, CFTC Chairman Selig announced the agency’s intention to advance new regulations covering leveraged retail trading of digital assets. This indicates a move by the CFTC to expand its regulatory focus beyond asset classification to encompass trading rules. Despite these steps, legislative efforts such as the CLARITY Act have stalled, underscoring the ongoing challenge of establishing a definitive regulatory framework through Congress.

    The guidance effectively moves these assets to the commodity side of the U.S. regulatory divide, supervised by the CFTC. However, the limitations of agency action versus legislative frameworks remain a key uncertainty. The classification provides a degree of regulatory clarity for major digital assets, but the future evolution of these rules may depend on further agency action or eventual congressional legislation.

    Why This Matters

    The materials describe a narrow update: The SEC and CFTC released a joint interpretive release classifying 16 major digital assets as ‘digital commodities’, moving them out of the securities classification. The long-term impact of agency guidance versus congressional action on comprehensive market structure rules.

    Broader Context

    Source materials place the factual news in this context: For an industry that spent years arguing over what its biggest tokens actually are, that is a short sentence with a long backstory.

  • Treasury Backs Down on Crypto Wallet Rules

    Treasury Backs Down on Crypto Wallet Rules

    Treasury Scraps Proposed Rules on Unhosted Crypto Wallets and Mixers

    The U.S. Treasury Department has withdrawn two significant proposed rules that would have imposed new reporting requirements on transactions involving unhosted cryptocurrency wallets and convertible virtual currency mixing services. The decision, announced by the Financial Crimes Enforcement Network (FinCEN), signals a shift in the regulatory approach to digital assets and resolves years of industry uncertainty.

    The first proposal, initially introduced in December 2020, aimed to require banks and money services businesses to maintain records for certain transactions involving unhosted wallets exceeding $3,000 and to report those surpassing $10,000. It also mandated that financial institutions gather and verify customer and counterparty information for specific transactions with private wallets.

    A separate proposal, put forth in 2023 under Section 311 of the USA PATRIOT Act, sought to designate transactions involving convertible virtual currency (CVC) mixers as a primary money laundering concern. This would have compelled financial institutions to collect and report data related to transactions utilizing these privacy-enhancing services.

    FinCEN stated that the withdrawals align with the administration’s objective to develop digital asset regulations that are “fit-for-purpose.” The move has been welcomed by cryptocurrency industry groups that had voiced strong opposition to the proposed measures. The Digital Chamber, for instance, indicated that the withdrawal alleviates regulatory pressure concerning self-custodial wallets.

    With these proposals rescinded, the crypto industry is no longer subject to the two frameworks, while existing anti-money laundering (AML) and financial regulations remain in effect. The withdrawn rules would have imposed additional obligations on regulated financial institutions when customers transferred cryptocurrency to private wallets. The Treasury’s decision means there is no new federal mandate compelling banks or exchanges to identify the owner of a self-hosted wallet solely based on a customer sending funds to it.